

Social Protection, Welfare Delivery, DBT and Employment Support
A complete UPSC Prelims and GS Paper II/III guide to social insurance vs social assistance, targeting errors and leakage, cash vs in-kind vs public services, JAM and Direct Benefit Transfer (DBT), shock-responsive federalism, NFSA 2013, and the statutory VB–G RAM G rural employment guarantee (in force from 1 July 2026).
Asha and Ravi operate a small roadside food stall. In normal months, their daily earnings cover groceries, room rent, school transport for their children, and regular medicines for Ravi’s elderly father, leaving a modest cash buffer. Then Ravi falls seriously ill and cannot work for several weeks. Instantly, a single shock squeezes the family from both sides: household income drops just as unavoidable medical treatment and hospital travel costs surge.
Private coping mechanisms help, yet none is guaranteed. Small savings quickly run dry; relatives may be struck by the same flood, drought, or local downturn; borrowing shifts purchasing power into the present only by creating a heavy future debt burden; and private insurance pays only if the household could afford regular premiums and the specific illness falls inside policy rules. Even rapid national GDP growth does not automatically shield a family at the exact moment an accident, illness, crop failure, maternity need, disability, or old-age loss of earning power strikes. Society therefore constructs a layered system called social protection — identifying each distinct risk or barrier, matching it with the right instrument (insurance, tax-funded assistance, food/health provision, or employment support), and ensuring the promise survives every step from formal eligibility to lived household security.
1. One System Needs Different Kinds of Support
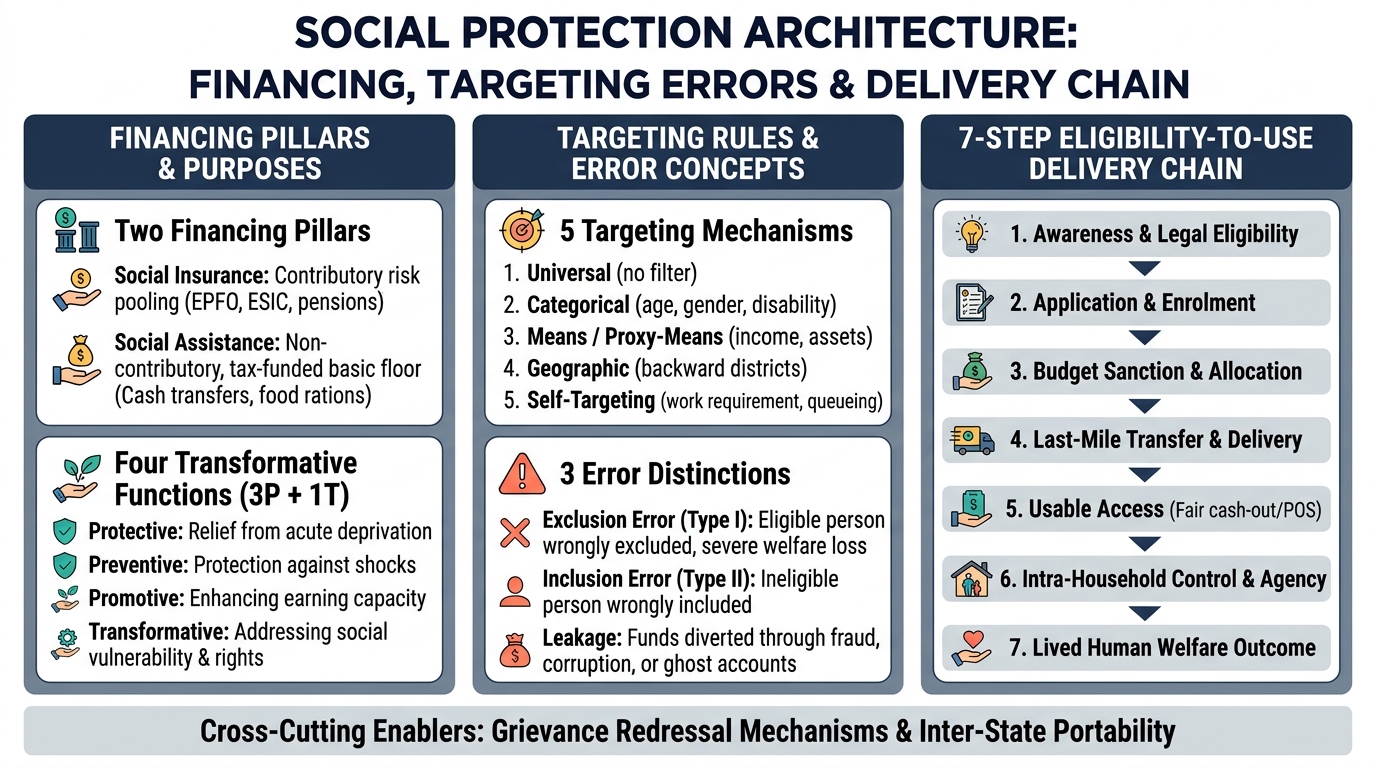
Because households confront very different kinds of vulnerability, no single welfare instrument can perform every job. A cash transfer restores general purchasing power; food rations or assistive devices secure access to specific essentials; functioning public clinics deliver skilled medical care that cash alone cannot conjure where doctors are absent; insurance spreads uncertain, catastrophic losses across a wide pool; and public employment or labour-market programmes supply earned income to adults able and willing to work.
Well-designed systems deliberately combine instruments when they solve different parts of the same problem: maternity protection pairs wage replacement with nutrition and antenatal care; old-age security pairs contributory pensions with tax-funded social pensions for lifetime informal workers; and rural public works provide lean-season wages today while building water-harvesting or road assets for tomorrow. Clarity begins by separating two analytical questions: (1) how support is financed and whether prior contributions are required, and (2) what form the delivered benefit takes (cash, in-kind good, service, subsidy, or work).
1.1 Insurance Pools Risk; Assistance Supports People Without a Contribution Condition
Four foundational distinctions govern the financing side of social protection in UPSC Prelims and Mains:
- Social Insurance (Contributory Risk Pooling): Workers, employers, or both contribute under statutory or common rules into a shared fund (often supplemented or subsidised by public revenue). Members who suffer a covered contingency — sickness, workplace injury, unemployment, maternity, disability, or old age — receive benefits even when their individual past contributions are far smaller than the cost of their claim. Unlike individual savings boxes, risk pooling shares uncertain losses across people and across time.
- Social Assistance (Non-Contributory Public Support): Financed out of general tax revenues without requiring any prior contribution record. Eligibility may be means-tested (based on low income or deprivation) or categorical/universal (covering all senior citizens, persons with specified disabilities, or children in a defined age group). Employer-mandated benefits and commercial private insurance form supplementary layers, but they cannot replace collective public floors where informal earnings are irregular or where covariate disasters strike whole regions simultaneously.
- Risk Pooling vs Redistribution: Risk pooling shares uncertain losses among covered members; redistribution shifts who bears financing costs and who receives support across income or social groups. Many public programmes combine both — for example, when tax revenues subsidise social-insurance premiums for unorganised workers or when contribution formulas charge higher earners more for a common health benefit.
- Consumption Smoothing: Social protection aims to prevent a sudden drop in earnings from forcing a sharp, damaging cut in food intake, medicines, or children’s schooling. Note the exam caution: consumption smoothing describes the purpose of protection, not proof that the household suffered zero loss (since late or partial benefits may still leave families strained).
1.2 Protection Can Relieve, Prevent, Promote and Transform
Social-policy scholarship classifies protection measures across four overlapping analytical lenses rather than four sealed departmental boxes:
- Protective (Relief): Provides immediate relief after deprivation or loss has occurred (such as destitute pensions, disaster relief, or emergency food rations).
- Preventive (Risk Mitigation): Reduces the likelihood that an economic or health shock pushes a vulnerable family into poverty (such as health/crop insurance, occupational safety standards, and timely primary care).
- Promotive (Capability & Livelihood Enhancement): Strengthens productive assets, skills, nutrition, or work opportunities so households can raise future autonomous earnings.
- Transformative (Equity & Inclusion): Addresses structural rules, stigma, or power imbalances that keep marginalised groups excluded — such as legal rights, disability-accessible procedures, portable migrant entitlements, and anti-discrimination safeguards.
A single statutory employment guarantee can act simultaneously as protective (lean-season wages), preventive (halting distress sale of livestock or tools), promotive (creating durable village irrigation assets), and transformative (raising rural women’s independent earnings and local bargaining power) — provided access, timely payment, and asset quality actually work on the ground.
2. Deciding Who Should Receive Support: Targeting, Errors and Leakage
Every welfare programme must define who qualifies. Choosing an eligibility rule involves unavoidable trade-offs among fiscal cost, benefit adequacy, administrative burden, stigma, and selection errors:
| Selection / Targeting Method | Core Rule | Main Advantage | Key Limitation / Vulnerability |
|---|---|---|---|
| 1. Universal Eligibility | Everyone inside a defined jurisdiction or population qualifies without an income test. | Avoids poverty-line cut-offs, minimises stigma and income-screening exclusion, and builds broad civic backing. | Expensive at generous benefit levels; under a fixed budget, wider coverage can dilute per-person adequacy; delivery/enrolment gaps can still exclude the marginalised. |
| 2. Categorical Targeting | Selects via an observable trait (older age, childhood, maternity, certified disability, occupation). | Simpler and less intrusive to verify than household income. | Category is an imperfect proxy: members of the same age or occupation vary widely in wealth and risk. |
| 3. Means / Proxy-Means Testing | Applies an income, consumption, or asset threshold to concentrate scarce public funds on poorer households. | Focuses higher per-beneficiary support within tight fiscal space. | Informal, seasonal incomes are hard to measure; static lists go stale quickly; families just above a rigid cut-off remain highly vulnerable. |
| 4. Geographic Targeting | Focuses resources on lagging blocks, drought-prone districts, or underserved settlements. | Effective where deprivation is spatially concentrated and household income data are weak. | Misses poor households living in richer districts and includes affluent households inside selected districts; out-migration erodes accuracy. |
| 5. Self-Targeting | Attaches a condition (such as manual public work at a statutory wage) that better-off individuals voluntarily avoid. | Eliminates complex administrative income verification while responding dynamically to distress. | Automatically excludes needy households unable to perform manual labour due to illness, disability, advanced age, pregnancy, or heavy caregiving duties. |
- Inclusion Error (Type II / Wrongful Inclusion): An ineligible person or household receives a targeted benefit despite not satisfying the eligibility rule.
- Exclusion Error (Type I / Wrongful Exclusion): A genuinely eligible person fails to receive the benefit — due to flawed proxy rules, outdated registries, missing documents, biometric/application hurdles, or payment failure.
- Leakage: A broader concept than inclusion error, encompassing mid-way pilferage/diversion of grain or funds, ghost/duplicate beneficiaries, fraudulent claims, and administrative loss before value reaches intended recipients. Even a universal programme (which has zero income-based inclusion error) can suffer serious leakage or exclusion if grain is diverted or remote hamlets remain unreached!
Over-engineering complex verification tests to eliminate every rupee of inclusion error often backfires by multiplying administrative costs, delays, humiliation, and exclusion of the poorest citizens. Moreover, because household realities change continuously — breadwinners lose jobs, children turn eighteen, disabilities occur, families split or migrate — static beneficiary lists decay rapidly unless paired with on-demand dynamic updating and accessible appeal mechanisms.
3. A Promise Must Travel from Eligibility to Actual Use
Public debates often treat a scheme as either “announced” or “absent”, ignoring the long operational chain connecting policy text to household security: Eligibility Rule → Public Awareness → Identification / Enrolment (and contribution recording where applicable) → Budget Availability & Sanction → Last-Mile Delivery (account credit / ration stock / clinic staffing / work allocation) → Usable Household Access & Control → Adequacy, Quality & Lived Outcome.
Keeping each link distinct prevents common analytical mistakes:
- Entitlement vs Legal Guarantee vs Budget vs Enrolment vs Receipt: An entitlement is a rule-backed claim; a legal guarantee embeds that claim in statute with enforceable duties and remedies; a budget allocation authorises fiscal spending; announced coverage states intended reach; and enrolment records a person in a database. None of those five proves actual timely receipt!
- Receipt vs Adequacy, Quality & Intra-Household Control: Even confirmed delivery fails if compensation arrives months after the lean season, foodgrain is spoiled, clinic reimbursement covers a tiny fraction of hospital bills, or cash credited to a household bank account cannot be accessed or controlled by the woman or elderly member for whom it was intended.
- Grievance Redressal (The Repair Path) & Portability (The Mobility Bridge): Because every stage can fail, credible welfare architecture requires a visible, low-burden grievance redressal process that accepts practical evidence, tracks complaints, enforces time-bound remedies, and flags systemic design bottlenecks. Equally, portability allows migrant and seasonal workers to carry verified eligibility or benefits across districts, states, or employers without losing protection at administrative borders.
4. Cash, Goods, Services and Lower Prices Work Differently
Once a target group is identified, policymakers must choose the form of benefit based on local market conditions and capability bottlenecks:
- Cash Transfers: Directly expand household purchasing power, honour consumer choice across diverse needs, and avoid physical grain movement and storage losses. However, cash loses real value during local food inflation, cannot buy skilled healthcare or schooling where facilities do not exist, and requires accessible cash-out points, active accounts, and intra-household control over phones and passbooks.
- In-Kind Goods (Foodgrains, Nutrition Take-Home Rations, Assistive Devices): Directly shield essential consumption when local markets are thin, remote, or price-volatile, and reinforce nutritional floors. Their trade-off lies in procurement, warehousing, transport, quality assurance, last-mile Fair Price Shop reliability, and narrower consumer choice.
- Direct Public Services (Clinics, Schools, Anganwadis, Care Centres): Deliver human capability directly — diagnosing illness, immunising children, and imparting foundational literacy. Cash transfers can pay bus fare to reach a hospital, yet cash alone cannot supply trained doctors, cold-chain vaccines, or safe classrooms; social-protection analysis therefore keeps service access and out-of-pocket financial protection tightly linked to sectoral service quality.
- Price Subsidies (Lower User Tariffs on Food, Cooking Fuel, Electricity, Transport, Farm Inputs): Reduce unit prices faced by users, but their true distributional incidence depends on who has physical connections/access, whether suppliers pass price cuts through, and how much each group consumes (broad untargeted price subsidies often channel larger absolute rupee benefits to heavier, wealthier users).
Mature welfare systems combine complements rather than forcing a single instrument to do everything: maternal and child nutrition, for example, works best when reliable food/micronutrient supply, maternity cash support for wage loss, and frontline health check-ups operate together.
5. Insurance, Assistance and Work Support Cover Different Risks
Matching instruments to risk structure explains why insurance, tax-funded assistance, active labour-market tools, and employment guarantees play distinct roles:
- Where Social Insurance Excels — and Where It Struggles: Risk pooling works best for idiosyncratic (independent) shocks (such as an individual appendectomy or road accident) where thousands of members pay into a pool and only a small, predictable fraction falls ill in any given month. Conversely, pure private or contributory insurance breaks down under three classic economic pressures:
- Covariate (Correlated) Shocks: When a cyclone, basin-wide flood, drought, or pandemic strikes an entire region simultaneously, thousands of claims arrive at the exact same moment, overwhelming local reserve pools unless backed by sovereign reinsurance or general tax budgets.
- Adverse Selection (Hidden Information Before Enrolment): If health insurance is purely voluntary and priced at an average premium, healthy households opt out while those anticipating expensive surgeries opt in—driving claims up and triggering a premium “death spiral” (solved by mandatory payroll/universal tax-funded pools like AB-PMJAY or ESIC!).
- Moral Hazard (Changed Behaviour After Coverage) & Informal Income Volatility: Covered hospitals may over-bill or over-prescribe diagnostics (requiring strict package rates and clinical audits), while informal workers with irregular seasonal earnings cannot sustain rigid monthly contributions without state co-contributions.
- Why Non-Contributory Assistance Remains Indispensable: Millions of citizens spend decades in unpaid family caregiving, subsistence farming, or casual work without unbroken payroll histories. Tax-funded assistance establishes a non-negotiable security floor in old age, widowhood, maternity, and disability, above which contributory schemes can build additional benefits.
- Active Employment Support vs Public-Works Guarantees: Job-matching portals, skill training, transport/hostel mobility support, and short-term hiring subsidies reduce frictional and skill barriers — yet training alone cannot manufacture missing aggregate labour demand. Conversely, a statutory public-works guarantee directly supplies lean-season wage employment, creates durable local ecological/village assets, and strengthens rural workers’ reservation wage and bargaining power against exploitative terms — though manual work can never substitute for disability pensions, maternity rest, healthcare, or old-age support.
6. Protection Changes Across a Life, Within a Household, and in Informal Work
Vulnerability evolves across the human lifecycle, and gaps at one stage compound risks at the next:
- Childhood & Adolescence: Early-life nutrition, immunisation, care, and schooling shape lifelong cognitive and earning potential; an unbuffered adult illness can pull adolescents out of school into premature labour or unpaid care.
- Working Age & Disability: Adults require maternity protection, workplace injury cover, sickness/unemployment buffers, and employment support, while persons with disabilities need both an income floor (compensating extra living/medical costs) and accessible transport, schooling, and workplaces.
- Old Age: Declining physical earning capacity alongside rising chronic health needs makes predictable pensions, geriatric care, and financial protection against hospital bills essential.
- Intra-Household Power & Informal/Migrant Realities: Households do not automatically pool resources equally: individual recognition, women-centred bank/phone access, child-care support at worksites, and safe local grievance channels determine who actually benefits. For informal, gig, and circular migrant workers whose employers and locations shift frequently, welfare systems must pair flexible contribution mechanisms with tax-funded floors and cross-border portability — remembering that portal registration alone does not equal active benefit coverage.
7. DBT and JAM Change Delivery, Not the Purpose of Welfare
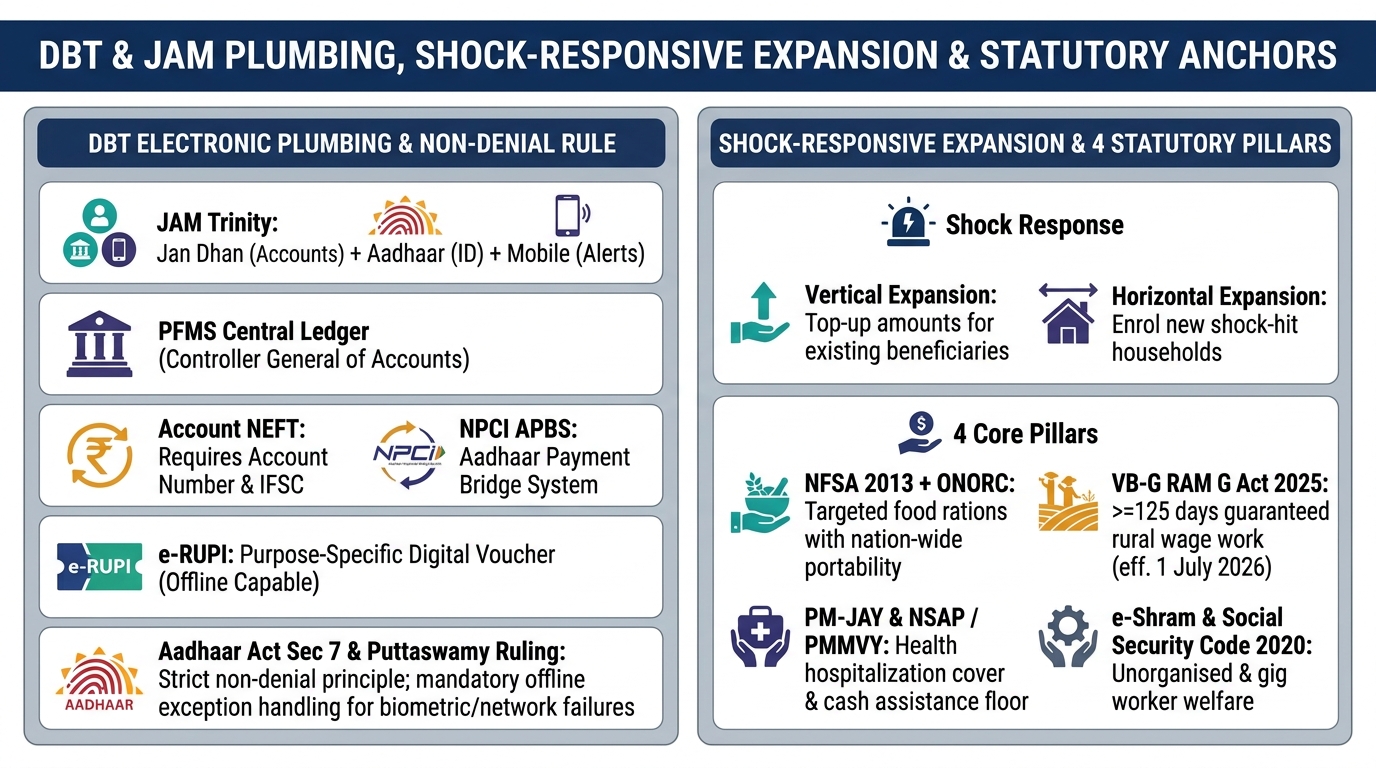
Historically, welfare funds and subsidised commodities passed through multiple administrative tiers, paper ledgers, and middlemen, creating payment delays and discretionary leakage. Direct Benefit Transfer (DBT) reorganises the delivery pipeline so cash transfers or subsidy equivalents travel electronically to verified beneficiary accounts, supported by the JAM enabling rails — Jan Dhan bank accounts (financial gateway), Aadhaar identity (record deduplication and verification), and Mobile communication (transaction alerts and information).
Analytical precision requires separating what digital rails solve from what they cannot solve:
- Delivery Mechanism ≠ Welfare Purpose or Entitlement: DBT and JAM neither define who deserves support nor set adequate benefit amounts; programme statutes and rules govern eligibility. Merely holding a bank account, Aadhaar number, and phone creates zero entitlement on its own.
- Digital Gains vs New Digital Failure Modes: Electronic rails remove ghost/duplicate entries, compress payment delays, and create auditable transaction trails. However, poorly designed digital gates introduce new exclusion risks: spelling mismatches across documents, worn fingerprints causing biometric authentication failure among manual labourers and seniors, inactive accounts or broken NPCI bank-mapper routing, weak rural connectivity, distant cash-out points, and shared household phones controlled by another family member.
- Mandatory Design Safeguards: Citizen-centric digital architecture requires clear failure notifications explaining why a payment bounced, offline/assisted exception handling so a technical glitch never cancels a lawful entitlement, strong data-privacy safeguards, and outcome audits beyond DBT transfer counts (measuring whether funds arrived on time, matched inflation, and remained under the intended recipient’s control).
7.1 Digital Payment Plumbings, e-RUPI Vouchers & Constitutional Non-Denial Safeguards
UPSC Prelims and GS Paper II/III frequently probe the institutional plumbing behind DBT as well as the legal safeguards governing Aadhaar-linked welfare:
- Public Financial Management System (PFMS), Single Nodal Agency (SNA/JIT) & Payment Rails: Administered by the Controller General of Accounts (Ministry of Finance), PFMS serves as the real-time fiscal nervous system linking Union/State treasuries to over 1,000 central and state schemes. Under the Single Nodal Agency (SNA) / Just-in-Time (SNA-SPARSH) reform, ministries no longer park thousands of crores of unspent Centrally Sponsored Scheme (CSS) funds in fragmented district commercial-bank accounts (which previously forced the Union Government to borrow and pay interest on idle cash floats!). Instead, funds remain in the Consolidated Fund / RBI and are released Just-in-Time only when a verified beneficiary payment file is generated on PFMS. Downstream transfers then travel via two distinct electronic rails: (a) Account-based rails (NEFT / RTGS) using the beneficiary’s explicit Bank Account Number + IFSC code, or (b) the Aadhaar Payment Bridge System (APBS) operated by NPCI, which uses the beneficiary’s Aadhaar number to route the credit automatically to whichever bank account was most recently seeded on the NPCI Aadhaar Mapper.
- Purpose-Bound Digital Vouchers (e-RUPI): Developed by NPCI, e-RUPI is a person-specific and purpose-specific prepaid digital voucher delivered via QR code or SMS string (usable even on basic feature phones without requiring a bank account or internet app by the beneficiary), bridging pure cash DBT and in-kind delivery for targeted nutrition, maternal health diagnostics, TB drugs, or input subsidies.
- Statutory & Constitutional Non-Denial Rule (Section 7, Aadhaar Act & Puttaswamy Judgment): While Section 7 of the Aadhaar (Targeted Delivery of Financial and Other Subsidies, Benefits and Services) Act, 2016 empowers governments to require Aadhaar authentication for Consolidated Fund welfare schemes, both the statute and the Supreme Court’s constitutional ruling in Justice K.S. Puttaswamy (Retd.) v. Union of India mandate alternative identification and offline exception-handling mechanisms so that no eligible child or citizen is ever deprived of a lawful welfare entitlement merely due to biometric or connectivity failure.
8. From Separate Programmes to an Adaptive Federal Protection System
When dozens of ministries run isolated welfare schemes, vulnerable families are forced to submit identical income, caste, disability, or residence certificates repeatedly across disconnected offices — while major lifecycle risks still fall through the cracks. Moving from fragmented schemes to an integrated social protection system rests on four pillars:
- Convergence Without Losing Accountability: Shared registries, common payment rails, and cross-referrals (linking a malnourished household simultaneously to rations, health care, and livelihood support) cut citizen compliance burdens, provided each agency’s legal responsibility for resolving errors remains crystal clear.
- Federal & Local Delivery Coordination: In India’s constitutional federation, Union legislation and central/shared financing interact with State beneficiary identification, top-up funding, and supply chains, while Panchayats, Urban Local Bodies, Fair Price Shops, Anganwadis, and Banking Correspondents execute last-mile enrolment, work allocation, distribution, and grievance hearings.
- Portability With Data Integrity: Interoperable registries allow migrants to retain food or health coverage across state lines, provided consent, cybersecurity, and swift local correction of erroneous database flags are built in (since a single giant database without error-correction can amplify exclusion nationwide).
- Shock-Responsive Expansion (Vertical & Horizontal): During floods, droughts, or economic crises, adaptive systems deploy vertical expansion (temporarily increasing benefit amounts or duration for existing beneficiaries) and horizontal expansion (rapidly enrolling newly shock-affected non-poor/near-poor families who were absent from older poverty lists) so households survive crises without selling tools, pulling children out of school, or falling into predatory debt traps.
9. India’s Durable Programme Families and Current Statutory Anchors
Studying Indian welfare by functional mechanism and legal form prevents rote confusion when scheme names evolve:
- Statutory In-Kind Food & Nutritional Entitlement — National Food Security Act (NFSA), 2013: Remains India’s core statutory framework covering up to $75\%$ of the rural population and $50\%$ of the urban population under two categories—Antyodaya Anna Yojana (AAY) households (the poorest of the poor, entitled to $35\text{ kg}$ of foodgrains per household per month) and Priority Households (PHH) (entitled to $5\text{ kg}$ per person per month)—alongside hot cooked meals and take-home rations for children and pregnant/lactating women, naming the eldest woman aged $18+$ as ration-card head (Section 13), and guaranteeing a legally enforceable Food Security Allowance (Section 8) in cash whenever the State fails to supply entitled foodgrains!
- Statutory Rural Wage-Employment Guarantee — 2025 VB–G RAM G Framework (In Force from 1 July 2026): As of August 2026, India’s statutory rural wage-employment anchor is the 2025 law establishing the VB–G RAM G mission, which came into force on 1 July 2026, repealing the Mahatma Gandhi National Rural Employment Guarantee Act, 2005 (MGNREGA) on that date (with statutory savings and interim transition arrangements). Under the current law, the statutory guarantee provides at least 125 days of wage employment in a financial year to every rural household whose adult members volunteer to do unskilled manual work. Two precision points are frequently tested: (1) the legal unit of guarantee is the rural household, not each individual adult; and (2) 125 days is a statutory ceiling-floor guarantee upon demand, not an automatic report that every household demanded or received 125 days — making work demand registration, timely allocation, wage payment, asset durability, and grievance redressal critical downstream stages.
- Cross-Cutting Welfare Delivery Architecture — Direct Benefit Transfer (DBT, Since 1 January 2013): Operating continuously since 1 January 2013, DBT functions not as a single welfare scheme but as an electronic transfer architecture carrying diverse cash entitlements, scholarships, pensions, and subsidy flows. Together, NFSA (in-kind legal entitlement), the VB–G RAM G guarantee (self-targeted employment support), and DBT (electronic payment rail) illustrate why delivery channels, food guarantees, and employment guarantees complement rather than replace one another.
9.1 Comparative Matrix of India’s Portable, Lifecycle & Informal-Worker Protection Pillars
Mapping India’s major social-protection anchors onto the chapter’s analytical framework clarifies how each pillar addresses a distinct risk, financing rule, and portability challenge:
| Protection Domain & Anchor | Financing & Benefit Form | Target Universe & Portability Design | Key Analytical Caution |
|---|---|---|---|
| 1. Food & Nutrition Security (NFSA, 2013 + ONORC) | Non-contributory statutory in-kind foodgrains + maternity/child nutrition. | Priority (PHH) & Antyodaya (AAY) households; One Nation One Ration Card (ONORC) enables inter-state/intra-state Fair Price Shop portability for migrants. | Legal right must still be checked against local stock, grain quality, e-POS exception handling, and intra-household nutrition sharing. |
| 2. Rural Employment Guarantee (2025 VB–G RAM G Act, from 1 Jul 2026) | Tax-funded, self-targeted manual wage employment + durable rural assets. | Guarantees at least 125 days/financial year per rural household whose adults volunteer for unskilled manual work (repealing MGNREGA, 2005 on 1 Jul 2026). | Unit is the household (not individual adult); 125 days is a demand-driven legal guarantee, not automatic receipt, and cannot replace disability/old-age care. |
| 3. Hospitalisation Risk Pool (Ayushman Bharat – PMJAY) | Non-contributory tax-funded health assurance (cashless secondary/tertiary care). | Deprived/vulnerable families plus expanded senior-citizen coverage; portable across empanelled hospitals nationwide. | Reduces catastrophic inpatient bills, yet requires strong outpatient primary care (Ayushman Arogya Mandirs) and local specialist supply. |
| 4. Lifecycle Social Assistance (NSAP & PMMVY) | Non-contributory tax-funded cash transfers via DBT. | Elderly, widows, and persons with severe disabilities (NSAP) plus maternity wage-loss/nutrition support (PMMVY). | Protects groups unable to perform manual work; impact hinges on real inflation-adjusted adequacy and timely credit. |
| 5. Unorganised Micro-Insurance & Pensions (e-Shram, PM-SYM, APY, PMJJBY, PMSBY) | Contributory / co-contributory risk pooling + Aadhaar-seeded registration. | e-Shram registers unorganised workers (16–59 yrs, non-EPFO/ESIC); APY/PM-SYM build old-age pensions; PMJJBY/PMSBY pool life & accident risk. | Portal registration ≠ active benefit coverage; irregular informal earnings can cause contribution lapses without auto-renewal/subsidy support. |
| 6. Statutory Labour Consolidation (Code on Social Security, 2020) | Unified statutory umbrella combining employer, worker, aggregator & state funds. | Subsumes 9 central social-security laws (EPF, ESIC, Maternity, Gratuity, Unorganised Workers) and formally defines gig workers and platform workers. | Translating statutory recognition of gig/platform workers into lived security depends on operationalised aggregator funds, portable IDs, and dispute remedies. |
10. Judging Protection by Design, Incentives, UBI Debate and Lived Access
Evaluating any proposed welfare reform — in UPSC Mains or policy practice — requires weighing five design dimensions together:
- Targeting vs Universality Trade-Offs: Universal floors eliminate exclusionary poverty tests and stigma at higher fiscal cost; tight means tests concentrate resources per poor household at the risk of exclusion errors and administrative friction.
- Work Incentives & Benefit Withdrawal Cliffs: Poorly designed income thresholds can create a harsh withdrawal cliff where earning ₹500 more causes a household to lose thousands of rupees worth of health or ration support overnight. Gradual benefit phase-outs, portable basic floors, and realistic contribution schedules for unstable informal earners protect work incentives far better than punitive cut-offs.
- Universal Basic Income (UBI) as One Option, Not a Complete System: An unconditional, periodic, universal individual cash transfer (UBI) simplifies targeting and maximises personal choice, yet its fiscal cost at meaningful adequacy is large — and cash alone cannot build a missing rural hospital, pool catastrophic surgical risk, or create productive local jobs. UBI is therefore one possible layer, never a wholesale replacement for public health, schooling, insurance, and employment policy.
- Fiscal Sustainability Aligned With Adequacy: Slashing benefits arbitrarily may flatter a single year’s fiscal deficit while gutting household protection; conversely, unfunded populist promises can collapse or crowd out essential health, education, and capital budgets. Sound architecture aligns benefit adequacy, coverage, tax/contributory financing, and state implementation capacity.
- Dignity, Assisted Access & Agency: True social protection treats citizens with dignity — pairing digital self-service with human assisted access for seniors, persons with disabilities, and low-literacy households, returning Asha and Ravi’s family from acute shock to autonomous livelihood rather than trapping them in bureaucratic humiliation or debt.
10.1 Concrete Worked Examples: Auditing Inclusion/Exclusion Errors & Leakage, Calculating Benefit Withdrawal Cliffs, and Matching Five Shocks to India’s Statutory Pillars
To apply these social-protection concepts with mathematical and legal precision in UPSC Prelims and GS Paper II/III Mains, work through these three concrete examples:
Scenario: A district contains $1,000\text{ households}$. Under a targeted nutrition-support rule, exactly $400\text{ households}$ are genuinely poor/eligible and $600\text{ households}$ are non-poor/ineligible. An independent social audit finds the following ground reality:
- Out of the $400$ genuinely eligible poor households, $300\text{ households}$ received ration cards and grain, while $100\text{ households}$ were left out (due to missing address documents or outdated survey lists).
- Out of the $600$ ineligible non-poor households, $60\text{ households}$ wrongfully obtained targeted ration cards.
- Additionally, the state depot dispatched $10,000\text{ kg}$ of grain for this district, including quotas for $40\text{ “ghost” (non-existent) cards}$, and $1,500\text{ kg}$ of grain was diverted to the open market before reaching Fair Price Shops.
- Exclusion Error (Type I Error — Share of Eligible Left Out): $$\text{Exclusion Error Rate} = \frac{\text{Eligible Households Excluded}}{\text{Total Genuinely Eligible Households}} = \frac{100}{400} = \mathbf{25.0\%}$$
- Inclusion Error (Type II Error — Ineligible Recipients): $$\text{Inclusion Error (as share of total real beneficiaries)} = \frac{60}{300 + 60} = \frac{60}{360} = \mathbf{16.7\%} \quad \left(\text{or }\frac{60}{600} = 10.0\%\text{ of non-poor}\right)$$
- Total Leakage (Broader Supply & Ghost Diversion + Wrongful Inclusion): Includes the $1,500\text{ kg}$ mid-way grain pilferage ($15\%$ of dispatched stock) plus the grain drawn against the $40$ ghost cards and $60$ ineligible cards! Notice why installing point-of-sale (e-POS) biometric verification can eliminate the $40$ ghost cards, yet if 15 elderly widows among the $300$ eligible households fail fingerprint authentication and are denied grain without an offline override, cutting leakage carelessly increases Exclusion Error!
Scenario: Suppose a state welfare scheme provides an annual health-and-education support package worth ₹20,000 to any household earning ₹1,00,000 or less per year, with a hard cut-off at ₹1,00,000:
- Case A (Hard Cut-Off / Withdrawal Cliff): Asha’s family currently earns ₹99,000 from her food stall and receives the ₹20,000 package, giving a total household command over resources of $₹99,000 + ₹20,000 = ₹1,19,000$. If Asha works extra hours to earn ₹3,000 more (bringing earned income to ₹1,02,000), the family crosses the ₹1,00,000 threshold and loses the entire ₹20,000 benefit overnight! Their net disposable resources drop from ₹1,19,000 to ₹1,02,000—a net loss of ₹17,000 for earning ₹3,000 more (an implicit Effective Marginal Tax Rate of $\frac{₹20,000}{₹3,000} = 666.7\%$!).
- Case B (Gradual Phase-Out Taper / Universal Floor): Suppose instead the benefit phases out smoothly at $20\text{ paise per rupee}$ ($20\%$ taper) earned above ₹1,00,000. When Asha’s income rises to ₹1,02,000 (₹2,000 above the threshold), her benefit trims by only $0.20 \times ₹2,000 = ₹400$ (retaining ₹19,600), so her family’s total resources rise to $₹1,02,000 + ₹19,600 = ₹1,21,600$—rewarding work effort while gradually targeting public funds!
Scenario: Match five members of an extended rural-migrant household to the exact Indian statutory/institutional pillar and explain why a single instrument could not serve all five:
- 1. Circular Migrant Construction Worker Moving from Bihar to Gujarat: Needs portable monthly foodgrains at a nearby urban Fair Price Shop without applying for a new state ration card → NFSA, 2013 + One Nation One Ration Card (ONORC) interoperable portability.
- 2. Rural Agricultural Household Facing Lean-Season Farm Worklessness in April–May: Adults are able and willing to perform unskilled manual work to earn wages and build village water-harvesting structures → 2025 VB–G RAM G Act (in force from 1 July 2026), providing a statutory demand-driven guarantee of at least 125 days of wage employment per financial year per rural household.
- 3. 72-Year-Old Grandmother Requiring Inpatient Cardiac Surgery: Cannot perform manual public works and has zero formal employer pension → requires non-contributory old-age social pension (NSAP) for daily living plus cashless secondary/tertiary hospitalisation cover under Ayushman Bharat – PMJAY.
- 4. Pregnant Mother Requiring Antenatal Check-Ups, Iron Supplements, and Wage-Loss Rest: Requires a three-part bundle → conditional maternity cash transfer via DBT (PMMVY) + take-home nutritious rations (Saksham Anganwadi / POSHAN 2.0 under NFSA) + clinical antenatal screening at an Ayushman Arogya Mandir (or purpose-bound e-RUPI diagnostic voucher).
- 5. Urban App-Based Food Delivery Rider (Platform Worker): Changes delivery platforms frequently without a traditional factory employer → formally recognised under the Code on Social Security, 2020 (defining gig workers and platform workers and enabling aggregator-contributed social security funds) alongside e-Shram portable registration.
UPSC CSE Prelims Previous Year Questions (PYQ Anchors)
Q1. Which of the following statements is/are correct regarding the ‘National Food Security Act, 2013’?
1. The families coming under the category of ‘below poverty line (BPL)’ only are eligible to receive subsidised food grains.
2. The eldest woman in a household, of age 18 years or above, shall be the head of the household for the purpose of issuance of a ration card.
3. Pregnant women and lactating mothers are entitled to a ‘take-home ration’ of 1600 calories per day during pregnancy and for six months thereafter.
Select the correct answer using the code given below:
(a) 1 and 2 only (b) 2 only (c) 1 and 3 only (d) 3 only
View Official Answer & Explanation
Correct Answer: (b) 2 only
Explanation: Statement 1 is incorrect because NFSA 2013 moved beyond legacy BPL-only framing to cover up to 75% of the rural population and 50% of the urban population under Priority Households (PHH) and Antyodaya Anna Yojana (AAY). Statement 2 is correct (Section 13 mandates women’s intra-household recognition by naming the eldest woman aged 18+ as household head on the ration card). Statement 3 is incorrect because nutritional norms specify 600 kcal (not 1600 kcal) take-home ration for pregnant and lactating women.
Q2. ‘Pradhan Mantri Jan-Dhan Yojana’ has been launched for:
(a) providing housing loan to poor people at cheaper interest rates
(b) promoting women’s Self-Help Groups in backward areas
(c) promoting financial inclusion in the country
(d) providing financial help to the marginalised communities
View Official Answer & Explanation
Correct Answer: (c) promoting financial inclusion in the country
Explanation: PMJDY forms the ‘J’ (Jan Dhan bank account) rail of the JAM trinity, providing universal access to basic zero-balance banking, RuPay debit cards, accident cover, and direct electronic receipt of DBT welfare transfers.
Q3. Regarding ‘Atal Pension Yojana’, which of the following statements is/are correct?
1. It is a minimum guaranteed pension scheme mainly targeted at unorganised sector workers.
2. Only one member of a family can join the scheme.
3. Same amount of pension is guaranteed for the spouse for life after subscriber’s death.
Select the correct answer using the code given below:
(a) 1 only (b) 2 and 3 only (c) 1 and 3 only (d) 1, 2 and 3
View Official Answer & Explanation
Correct Answer: (c) 1 and 3 only
Explanation: Atal Pension Yojana (APY) is a contributory social-insurance pension scheme for unorganised workers aged 18–40 offering guaranteed monthly pensions (₹1,000 to ₹5,000 after age 60), continuing at the same guaranteed level to the spouse after the subscriber’s death. Statement 2 is false because any eligible individual (including multiple members in a household) with a bank account can subscribe.
Q4. Consider the following statements in the context of interventions being undertaken under Anaemia Mukt Bharat Strategy / Maternal & Child Health-Nutrition convergence:
Which principle best explains why India pairs nutritional supplementation and conditional maternity cash transfers with public health check-ups rather than relying on cash transfers alone?
(a) Cash transfers automatically reduce household food demand
(b) Cash expands purchasing power, whereas clinical diagnostics, micronutrient supply, and immunisation require functioning public-health delivery
(c) In-kind services carry zero fiscal cost for State Governments
(d) Price subsidies replace the need for primary health centres
View Official Answer & Explanation
Correct Answer: (b)
Explanation: Cash transfers address household liquidity constraints and wage loss, but cannot substitute for absent clinical screening, iron-folic supplementation, cold-chain vaccines, or skilled birth attendance — illustrating why cash, in-kind nutrition, and direct public services act as complements.
Quick Revision Takeaways for Prelims & Mains
- Financing vs Form: Social insurance pools risk via contributions; social assistance funds non-contributory support via general taxes. Either can deliver cash, goods, services, or pensions.
- Four Analytical Lenses: Protective (relief), Preventive (risk mitigation), Promotive (capability/income growth), and Transformative (inclusion/rights/agency).
- Error Precision: Inclusion error = ineligible gets targeted benefit; Exclusion error = eligible misses out; Leakage = broader loss including diversion, duplicates, and fraud (can afflict universal schemes too!).
- DBT & JAM (DBT since 1 Jan 2013): Electronic delivery rails, NOT eligibility rules. Must pair deduplication gains with offline exception handling and intra-household access checks.
- Shock-Responsive Systems: Vertical expansion increases support to existing beneficiaries; horizontal expansion enrols newly crisis-hit households.
- Current Statutory Anchors (as of Aug 2026): NFSA 2013 (statutory food/nutrition entitlement) and the 2025 VB–G RAM G Act (in force 1 July 2026, repealing MGNREGA 2005; guarantees at least 125 days of unskilled manual wage employment per financial year per rural household).
Prelims Practice MCQs (8 Conceptual & Current Statutory Questions)
MCQ 1. Which of the following most accurately distinguishes ‘social insurance’ from ‘social assistance’?
(a) Social insurance always delivers in-kind goods, whereas social assistance always delivers cash.
(b) Social insurance pools risks across members subject to contribution rules (even when partially tax-subsidised), whereas social assistance provides tax-funded support without requiring prior contributions.
(c) Social insurance is restricted exclusively to private commercial companies.
(d) Social assistance necessarily requires a strict household income test in every programme.
Show Answer
Answer: (b) — Social assistance does not require a contribution history and may be means-tested, categorical, or universal; social insurance pools risk around contributory membership rules (often with state co-contributions).
MCQ 2. Consider a universal nutrition programme in a district where no income cut-off applies, every child aged 3–6 years is eligible, yet 15% of procured grain is diverted before reaching local centres and remote hamlets lack centres altogether. Which combination best describes this situation?
(a) High income-based inclusion error, zero leakage, and zero exclusion
(b) Zero income-based inclusion error, alongside both supply leakage and practical exclusion of eligible children
(c) Pure self-targeting with zero administrative cost
(d) Complete consumption smoothing across all households
Show Answer
Answer: (b) — Without an income eligibility test there is no income-based inclusion error, yet diversion constitutes leakage and unreached eligible children suffer exclusion.
MCQ 3. With reference to India’s statutory rural wage-employment framework in force from 1 July 2026, consider the following statements:
1. The 2025 law establishing the VB–G RAM G mission came into force on 1 July 2026, repealing the Mahatma Gandhi National Rural Employment Guarantee Act, 2005 with transitional savings.
2. It guarantees at least 125 days of wage employment in a financial year to every individual adult residing in a rural household.
Which of the statements given above is/are correct?
(a) 1 only (b) 2 only (c) Both 1 and 2 (d) Neither 1 nor 2
Show Answer
Answer: (a) 1 only — Statement 1 is correct. Statement 2 is a classic UPSC unit trap: the guarantee of at least 125 days in a financial year applies to each rural household whose adult members volunteer for unskilled manual work, NOT separately to every individual adult.
MCQ 4. During a severe cyclone, a State Government first doubles the monthly cash transfer paid to existing social-pensioners and then opens rapid mobile registration camps to enrol newly displaced coastal artisans who were previously above the poverty threshold. In social-protection terminology, these two steps correspond respectively to:
(a) Horizontal expansion followed by vertical expansion
(b) Vertical expansion followed by horizontal expansion
(c) Self-targeting followed by price subsidisation
(d) Contributory risk pooling followed by benefit withdrawal
Show Answer
Answer: (b) — Topping up benefits for existing enrollees is vertical expansion; extending coverage to newly shock-hit households is horizontal expansion.
MCQ 5. Why can a self-targeted manual public-works guarantee NOT serve as a household’s sole social-protection instrument across the lifecycle?
(a) Public works never generate rural community assets.
(b) Manual work requirements naturally exclude persons unable to perform physical labour due to severe disability, illness, advanced age, late pregnancy, or full-time infant care.
(c) Wage employment reduces worker bargaining power in local labour markets.
(d) Self-targeting requires detailed annual income-tax audits of every villager.
Show Answer
Answer: (b) — Self-targeting via manual work screens out non-needy seekers without an income test, but cannot protect needy individuals physically or socially unable to perform manual work.
MCQ 6. Which of the following statements best captures the role of Direct Benefit Transfer (DBT) and the JAM trinity in Indian welfare policy?
(a) DBT is a standalone central pension scheme launched in 2020 that replaces the National Food Security Act.
(b) Possessing a Jan Dhan account, Aadhaar number, and mobile phone automatically entitles every citizen to monthly cash assistance.
(c) DBT (launched on 1 January 2013) is an electronic delivery architecture whose success still depends on upstream eligibility rules, exception handling for technical failures, local supply of services, and intra-household control.
(d) Digital DBT eliminates the need for grievance redressal mechanisms.
Show Answer
Answer: (c) — DBT reorganises payment delivery; eligibility, adequacy, exception handling, and real-world access remain decisive.
MCQ 7. A welfare scheme withdraws a ₹24,000 annual health-and-scholarship package completely the moment a household’s measured annual income rises from ₹99,500 to ₹1,00,500. This design flaw is known as:
(a) Covariate risk pooling
(b) A benefit withdrawal cliff (high effective marginal penalty on additional earnings)
(c) Portable convergence
(d) Transformative universalism
Show Answer
Answer: (b) — Abrupt cut-offs penalise small income gains; gradual phase-outs or universal/categorical floors mitigate withdrawal cliffs.
MCQ 8. When flood waters hit an entire river basin simultaneously, why does pure private commercial insurance struggle more than in the case of isolated road accidents?
(a) Floods are covariate (positively correlated) shocks hitting thousands of policyholders at the exact same time, straining private risk pools without public reinsurance or fiscal backing.
(b) Floods create zero income or asset loss for households.
(c) Road accidents affect every citizen on the same day.
(d) Private insurers are legally barred from charging premiums for any risk.
Show Answer
Answer: (a) — Insurance pooling works smoothest when losses are independent across members; covariate disasters hit entire communities together.
GS Paper II & III Mains Practice Questions
Mains Q1 (GS Paper II / III — 15 Marks, 250 Words): “Direct Benefit Transfer (DBT) and the JAM trinity transform how welfare travels, not why welfare exists or whether essential public services work.” Examine this statement by comparing cash transfers, in-kind food security, and direct public services in India’s social-protection architecture.
Structuring Blueprint:
- Introduction: Define DBT (operating since 1 Jan 2013) and JAM as electronic delivery rails within India’s layered social-protection system.
- What DBT + JAM Solve: Deduplication, disintermediation, faster electronic settlement, and fiscal auditability.
- Why Delivery ≠ Welfare Purpose or Service Supply: Contrast cash purchasing power with in-kind nutrition security (NFSA 2013 in volatile/thin markets) and direct public capability provision (clinics, schools); analyse digital exclusion risks (biometric/seeding mismatches, last-mile cash-out distance, intra-household phone/account control) requiring assisted access and enforceable grievance redressal.
- Conclusion: Recommend problem-led complementarity — pairing portable digital rails with strong frontline health/education systems and accountable local governance.
Mains Q2 (GS Paper III — 15 Marks, 250 Words): Why does an economy with a large informal and mobile workforce require a multi-pillar social-protection system combining non-contributory assistance, portable social insurance, and statutory rural employment support? Discuss with reference to India’s current statutory anchors.
Structuring Blueprint:
- Introduction: Highlight lifecycle and shock vulnerabilities when earnings are informal, seasonal, or geographically mobile.
- Complementary Roles of the Three Pillars: (1) Tax-funded social assistance for unpaid caregivers, seniors, and persons with disabilities lacking contribution histories; (2) adapted/portable social insurance for health, maternity, injury, and pensions; and (3) self-targeted rural employment support under the 2025 VB–G RAM G statutory framework (in force from 1 July 2026; 125-day household guarantee) alongside urban/migrant portability and shock-responsive vertical/horizontal expansion.
- Conclusion: Emphasise bridging formal legal guarantees to lived access via timely payments, quality community assets, portability across state borders, and dignified grievance redress.
Frequently Asked Questions (FAQs)
Q1. Does a budget allocation or beneficiary enrolment number prove that households received social protection?
No. Budget allocations authorise funds and enrolment records names in a registry, whereas real protection requires every downstream step to succeed: awareness, sanction, timely payment or stock delivery, physical and intra-household usability, adequacy against local prices, and effective grievance redressal when errors occur.
Q2. What changed on 1 July 2026 in India’s statutory rural wage-employment guarantee?
On 1 July 2026, the 2025 law establishing the VB–G RAM G mission came into force (repealing MGNREGA, 2005 with transitional savings). It provides a statutory guarantee of at least 125 days of wage employment in a financial year to each rural household whose adult members volunteer for unskilled manual work.
Q3. Can Universal Basic Income (UBI) replace all existing food, health, education, and employment programmes?
No. While an unconditional universal cash payment simplifies eligibility and enhances choice, cash by itself cannot build a missing primary health centre, staff a school, insure catastrophic surgery costs, or create local productive jobs — making UBI one debated cash option rather than a complete welfare system.
11. Primary Statutory Acts, Supreme Court Rulings & Official Sources
- Core Welfare & Labour Statutes: National Food Security Act, 2013 (Sections 3, 8, 13); 2025 Act establishing the VB–G RAM G Rural Employment Framework (in force from 1 July 2026, repealing MGNREGA 2005 with transitional savings; guaranteeing at least 125 days of wage employment per rural household); Aadhaar (Targeted Delivery of Financial and Other Subsidies, Benefits and Services) Act, 2016 (Section 7); and Code on Social Security, 2020.
- Constitutional Jurisprudence: Supreme Court of India, Justice K.S. Puttaswamy (Retd.) & Anr. v. Union of India & Ors. (mandating proportionality and non-denial of lawful welfare entitlements due to biometric/technical authentication failure).
- Official Digital & Administrative Frameworks: Controller General of Accounts (Ministry of Finance), Public Financial Management System (PFMS) & Single Nodal Agency (SNA / SNA-SPARSH Just-in-Time) Guidelines; Direct Benefit Transfer (DBT) Mission (Cabinet Secretariat); NPCI Aadhaar Payment Bridge System (APBS) & e-RUPI Digital Voucher specifications; and ILO World Social Protection Report.