

The 1991 Crisis, LPG Reforms and India’s Continuing Reform Agenda
A complete UPSC Prelims and GS Paper III Economy guide explaining how India’s 1991 balance-of-payments emergency unfolded, why macroeconomic stabilisation differs from structural reform, how Liberalisation, Privatisation, and Globalisation reshaped incentives and state capacity, and how to evaluate India’s continuing reform agenda.
Every economy buys essential goods from the rest of the world — crude oil, capital machinery, fertilisers, medicines, or electronic components — that ordinarily have to be paid for in usable foreign currency. So long as foreign-currency earnings from exports and remittances, supplemented by sustainable investment and borrowing, cover external payments and loan instalments, international trade runs smoothly. Danger erupts when two forces collide: scheduled debt repayments and import bills continue falling due just as overseas lenders and depositors lose confidence and stop supplying fresh foreign exchange, rapidly draining the central bank’s reserve buffer.
When that emergency strikes an economy simultaneously constrained by pervasive domestic licensing and high trade barriers, policymakers face two distinct jobs. First comes macroeconomic stabilisation — containing the immediate payments breakdown through temporary external finance, fiscal consolidation, tighter monetary/credit discipline, and exchange-rate adjustment. Second comes structural reform — redesigning the rules and institutions governing industrial entry, competition, trade, finance, and public enterprises so resources are used more productively and future vulnerability falls. The familiar shorthand LPG (Liberalisation, Privatisation, and Globalisation) summarises major directions of that structural shift, not a single statute, a single July 1991 date, or a claim that the state disappeared.
1. When Foreign Currency Stops Arriving
Consider how a country pays its external bills from year to year. Exports of goods and services earn foreign currency, while inward remittances from citizens working abroad, foreign direct and portfolio investment, and external loans bring additional foreign exchange in. Borrowing abroad is not automatically reckless: an external loan that finances efficient ports, reliable power networks, or competitive export factories can generate the future income and foreign-exchange earnings needed to service that debt comfortably.
Vulnerability turns acute when persistent excesses of current foreign-currency payments over current earnings rely on short-term or confidence-sensitive borrowing, and lenders suddenly refuse to roll over maturing loans while depositors withdraw funds. Authorities must then draw down official foreign-exchange reserves kept as a safety buffer. Once that buffer shrinks to a few weeks of imports, even fuel, fertiliser, medicine, and scheduled debt-service payments come under threat. If domestic producers simultaneously require repeated administrative permissions to open a plant, expand capacity, import a machine, or upgrade technology — while high import protection dulls competitive pressure to lower cost or improve quality — the economy cannot quickly export its way out of trouble. That twin predicament defined India’s watershed moment in mid-1991: immediate stabilisation was needed to stop the external payments crisis from worsening, while deeper structural reform was needed to unlock productive efficiency.
2. Why India Had Built a Controlled Economy
India’s pre-1991 economic architecture grew out of concrete historical conditions at Independence in 1947 rather than abstract dogma. Newly independent India faced mass poverty, low domestic savings, weak infrastructure, scarce long-term private capital, and a narrow industrial base, alongside understandable caution toward foreign exchange dependence. Private business houses could not by themselves finance all the steel plants, heavy engineering works, multipurpose dams, power grids, transport networks, and scientific institutes required for modern industrialisation.
India therefore built a mixed economy — never a Soviet-style total command economy without private property or markets, yet one in which the state assumed the “commanding heights”. Public-sector enterprises entered core infrastructure, heavy industry, mining, energy, banking, and insurance; import substitution sheltered infant domestic industries behind tariffs and quantitative import quotas so they could learn to manufacture at home; and industrial licensing sought to channel scarce capital toward planned priorities, curb concentration of private economic power, and promote balanced regional development. Crucially, this pre-reform era built real national capabilities: a diversified industrial base, higher technical and scientific institutions, development banks, domestic capital-goods capacity, and an experienced entrepreneurial and managerial class without which post-1991 growth in pharmaceuticals, engineering, automobiles, and information technology could not have taken off in the same way.
2.1 When Guidance Turned into a Barrier
As the industrial economy grew more complex between the 1960s and 1980s, instruments designed for post-Independence scarcity increasingly outlived their original purpose and hardened into barriers against productivity:
- The Licence-Permit-Control System: Under the Industries (Development and Regulation) Act, 1951, Monopolies and Restrictive Trade Practices (MRTP) Act, 1969, and Foreign Exchange Regulation Act (FERA), 1973, firms frequently needed prior government approval to enter an industry, expand existing capacity, diversify product lines, choose a factory location, import capital goods, or sign a foreign technology collaboration. Large business houses faced pre-entry asset-threshold clearance, while hundreds of manufactured items were reserved exclusively for the public sector or small-scale units. Ironically, licensing often shielded incumbent producers from capable domestic rivals, turned licences into scarce assets commanding economic rents, delayed technological upgrading, and rewarded lobbying over shop-floor innovation.
- High Trade Protection & Input-Cost Penalties: Quantitative restrictions (import licences and bans) combined with some of the world’s highest customs tariffs insulated domestic producers from external competition. Firms could survive despite high costs, outdated designs, and long delivery delays — and expensive, low-quality domestic steel, chemicals, or machinery penalised downstream Indian manufacturers trying to compete in export markets.
- Financial Repression: Interest rates on deposits and loans were largely administered, while high Statutory Liquidity Ratio (SLR) and Cash Reserve Ratio (CRR) pre-emptions compelled commercial banks (nationalised in 1969 and 1980) to park a large share of incremental deposits in low-yield government securities alongside directed credit targets. While these rules expanded rural banking reach and financed public plans, they also compressed flexible risk pricing, muted competition among banks, and constrained credit allocation toward dynamic productive opportunities.
- Mixed Public-Enterprise Performance: While several Central and State Public Sector Enterprises (PSEs) built vital strategic and infrastructural capacity, many others suffered from blurred commercial versus social mandates, soft budget constraints, political interference, overstaffing, and chronic financial losses that absorbed scarce budgetary resources needed for health, schooling, and infrastructure.
- The 1980s Prelude — Faster Growth Alongside Rising Vulnerability: Policy change did not begin from zero in July 1991. During the 1980s, selective delicensing (“broad-banding”), capital-goods import relaxation, and technology modernisation helped push real GDP growth above 5% per year. Yet that faster growth was accompanied by widening fiscal deficits, heavier domestic and external borrowing, and rising import bills — setting up a fragile macroeconomic balance.
3. Six Economic Objects That Must Remain Separate
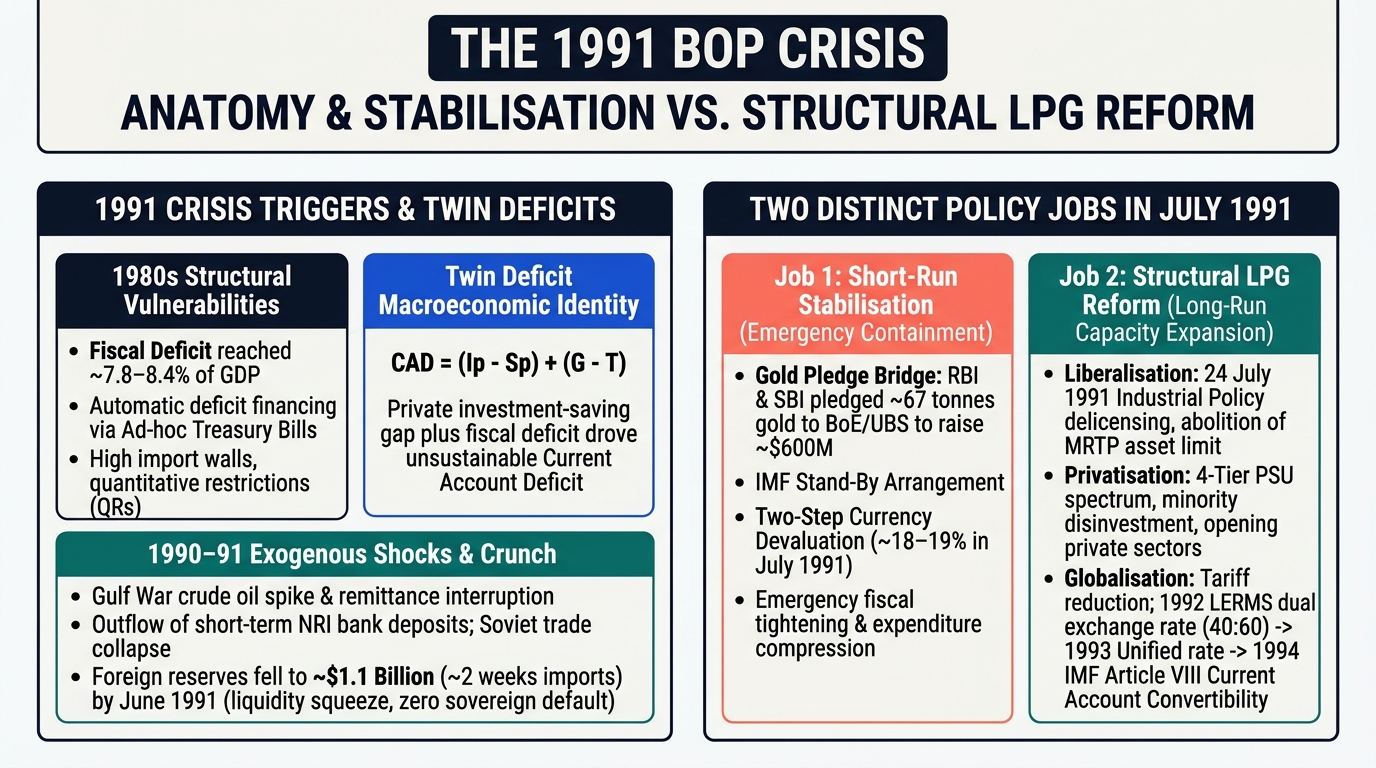
Exam questions frequently test whether candidates can keep six related macroeconomic concepts strictly distinct across accounts, time horizons, and institutional balance sheets.
3.1 The Government’s Gap Is Not the Country’s Foreign Gap
Three flow accounts measure very different balances during a given year:
- Fiscal Deficit (Government Budget Account): Arises when a government’s total expenditure exceeds its revenue receipts plus non-debt capital receipts during a fiscal year, requiring borrowing. Persistent fiscal deficits raise public debt and interest burdens, add to aggregate demand, and can erode lender confidence.
- Current Account Deficit — CAD (External Current Account): Belongs to the entire nation’s external interactions — both public and private — not merely the Union Budget. A CAD arises when current foreign-currency payments (merchandise and service imports plus primary investment-income outflows) exceed current receipts (goods and service exports, primary income inflows, and secondary transfers such as diaspora remittances). Although a high fiscal deficit can widen the CAD by boosting aggregate demand and imports (the “twin-deficit” channel), the two are not identical. To see the exact link, write the macroeconomic national income accounting identity connecting domestic saving, investment, the government budget, and the external current account: $$\text{CAD} \equiv (I_p - S_p) + (G - T)$$ where $I_p$ is private investment, $S_p$ is private domestic saving, and $(G - T)$ is the government’s fiscal deficit. This equation shows immediately that a rising fiscal deficit $(G - T > 0)$ widens the nation’s Current Account Deficit ($\text{CAD}$) whenever private domestic saving does not exceed private investment by enough to absorb the government’s borrowing—yet private saving, private corporate investment, exchange rates, and global commodity prices also independently move the CAD!
- Balance of Payments — BoP (Complete External Account): Encompasses both the Current Account and the Capital/Financial Account plus official reserve movements. As a double-entry accounting statement, the BoP always sums to zero once financing entries and reserve changes are counted. A BoP crisis therefore never means the accounting table failed to balance; it means normal voluntary external financing has dried up on acceptable terms, forcing rapid reserve depletion, emergency official borrowing, or painful import compression.
3.2 What Is Owed, What Falls Due, and What Is Held in Reserve
Three stock-and-flow indicators govern external liquidity and solvency:
| Economic Object | Stock or Flow? | Exact Definition & Institutional Scope | Why Precision Matters in the 1991 Context |
|---|---|---|---|
| 1. Fiscal Deficit | Flow (per year) | Government’s borrowing requirement inside the domestic/external fiscal budget. | India’s combined Centre–State fiscal gap widened sharply in the late 1980s (Centre’s gross fiscal deficit ~7.8%–8.4% of GDP by 1990–91), fuelling demand and automatic RBI monetisation. |
| 2. Current Account Deficit (CAD) | Flow (per year) | Economy-wide gap between current external payments and current external receipts. | India’s CAD reached roughly 3% of GDP in 1990–91 — dangerous because export earnings were sluggish and short-term external financing suddenly reversed. |
| 3. Balance of Payments (BoP) | Flow statement | Total current + capital/financial transactions with non-residents plus reserve settlement. | A BoP crisis means autonomous capital inflows no longer cover the CAD + maturing debt, forcing emergency reserve drawdown. |
| 4. External Debt | Stock (at a date) | Total outstanding debt owed by residents (government + firms) to non-residents. | Moderate total debt on long, concessional terms can be safe; rising short-term commercial debt in the late 1980s created acute rollover vulnerability. |
| 5. Debt Service | Flow (per period) | Principal instalments + interest payments actually falling due during a period. | When commercial lenders refused rollover and NRI deposits exited in 1990–91, immediate foreign-currency cash outflow spiked regardless of long-term asset wealth. |
| 6. Foreign-Exchange Reserves | Stock (at a date) | External liquid assets (foreign currency assets, gold, SDRs, IMF reserve tranche) held by the RBI — not ordinary government Budget cash. | Foreign-currency assets plunged to roughly USD 1.1–1.2 billion by mid-1991 (barely two to three weeks of essential imports), creating an acute foreign-currency liquidity emergency. |
Keeping these six objects separate explains why casual headlines claiming “India went bankrupt in 1991” are analytically loose. India never defaulted on its sovereign obligations; rather, it confronted a severe foreign-currency liquidity emergency for payments falling immediately due, compounded by deeper fiscal and export-competitiveness weaknesses.
4. How Vulnerability Turned into the 1991 Crisis
India’s 1991 emergency resulted from an interaction between structural vulnerabilities accumulated during the 1980s and proximate shocks during 1990–91. Throughout the 1980s, rising government revenue deficits and borrowing were partly financed by automatic creation of Reserve Bank of India credit through ad-hoc Treasury Bills. How did that automatic monetisation mechanism actually work? Under an administrative arrangement begun in the 1950s, whenever the Union Government’s cash balance with the RBI fell below a tiny statutory floor (₹50 crore at the end of a week), the RBI automatically issued 91-day ad-hoc Treasury Bills at a fixed, artificially low discount rate ($4.6\%$ per annum) and credited freshly created reserve money ($M_0$) to the government’s account—which was never actually retired at maturity! Because every rupee of central-bank reserve money multiplied into broader commercial-bank money supply ($M_3$), automatic deficit monetisation fuelled inflation and import demand while neutering independent monetary policy (until the historic 1994 and 1997 RBI–Government Supplemental Agreements abolished ad-hoc T-Bills completely from April 1997 and replaced them with strictly capped, market-rate Ways and Means Advances [WMA]). On the external front, strong domestic demand drew in imports while protected, high-cost domestic industry struggled to expand exports rapidly. Widening current-account deficits were increasingly bridged through external commercial borrowings (ECBs), short-term trade credit, and Non-Resident Indian (NRI) foreign-currency deposits — liabilities sensitive to investor confidence and requiring regular renewal.
Against that fragile backdrop, multiple proximate shocks hit simultaneously in 1990–91: Iraq’s invasion of Kuwait in August 1990 (the Gulf Crisis) drove up global crude-oil import bills and disrupted West Asian trade and worker remittances; economic dislocation in the Soviet bloc weakened rupee-payment export markets; and rapid domestic political turnover (three Prime Ministers between 1989 and mid-1991, plus a delayed Union Budget) shook international lender confidence. Credit-rating agencies downgraded India; foreign commercial banks stopped rolling over short-term credit; and net NRI deposit inflows turned into outflows. Tightening administrative import curbs to save dollars starved factories of fuel, spare parts, and raw materials, depressing industrial production and exports further. Thus, the Gulf conflict acted as a powerful trigger, not the sole cause: without accumulated 1980s fiscal and external fragility the oil shock need not have sparked a near-default crisis, and without the shock and confidence reversal the underlying weakness might not have erupted at that exact moment.
4.1 Emergency Finance Bought Time
To honour every scheduled debt payment and keep essential imports flowing while longer-term policies were put in place, Indian authorities mobilised bridge liquidity from multiple sources:
- Gold-Backed Bridge Liquidity: Using confiscated/government gold leased via the State Bank of India and approximately 47 tonnes of RBI monetary gold physically pledged abroad to the Bank of England and the Bank of Japan in July 1991, India raised roughly USD 600 million in emergency short-term liquidity. Far from “selling away all the nation’s gold forever”, this acted strictly as collateralised bridge finance — and the pledged RBI gold was redeemed later in 1991 once reserves stabilised.
- Distinct Roles of the IMF, World Bank & Bilateral Partners: India accessed emergency drawings and Stand-By / Compensatory and Contingency Financing Facility (CCFF) arrangements from the International Monetary Fund (IMF) — whose mandate centred on macroeconomic stabilisation and balance-of-payments liquidity — alongside structural adjustment support from the World Bank and Asian Development Bank plus bilateral assistance (notably Japan).
- Balanced Understanding of Conditionality: Multilateral financing carried agreed policy commitments (conditionality) on fiscal deficit targets, monetary restraint, and structural opening. It is historically inaccurate either to claim that external lenders had zero influence or to claim that Washington wrote every Indian reform from scratch: Indian economists and policymakers had debated delicensing, trade reform, and financial modernisation throughout the 1980s, and the government led by Prime Minister P. V. Narasimha Rao and Finance Minister Dr Manmohan Singh designed, sequenced, and politically owned the reform programme.
5. Stabilisation Came Before Lasting Recovery
Before structural reforms could bear fruit over years, macroeconomic stabilisation had to halt the immediate drain on reserves and restore domestic and external confidence. The Union Budget of July 1991 initiated sharp fiscal consolidation (targeting a reduction of the Centre’s fiscal deficit from over 8% of GDP toward 6.5% and lower), paired with tight monetary and credit restraint to cool excess demand and double-digit inflation, alongside temporary import compression and emergency external financing.
Exchange-rate adjustment formed a pivotal leg of stabilisation. Operating under an administered basket-linked exchange regime, the Reserve Bank of India carried out a two-step downward adjustment of the rupee on 1 July and 3 July 1991 (cumulatively about 18–19% against major currencies). In precise macroeconomic terminology, a deliberate official downward revision of a currency’s fixed or administered par value is called a devaluation, whereas a market-driven fall under a floating or market-linked exchange regime is called depreciation.
A weaker rupee raises the rupee price of imports and gives Indian exporters more rupees per unit of foreign currency earned (UPSC Prelims 2019 / 2022). Yet trade balances rarely improve instantaneously: existing trade contracts fix short-run volumes (creating a possible initial J-curve effect), exporters need reliable power, credit, port logistics, and foreign buyer demand to expand supply, imported crude oil and intermediate components become costlier in rupees, and existing foreign-currency debt becomes heavier in domestic-currency terms. Moreover, short-run fiscal and credit tightening can temporarily slow output and employment — making the composition of fiscal adjustment (protecting health, primary education, and core infrastructure maintenance rather than slashing productive capital spending indiscriminately) critical. Above all, stabilisation restores solvency and breathing room; only structural reform raises long-run economy-wide productivity.
6. Structural Reform Changed Rules and Incentives
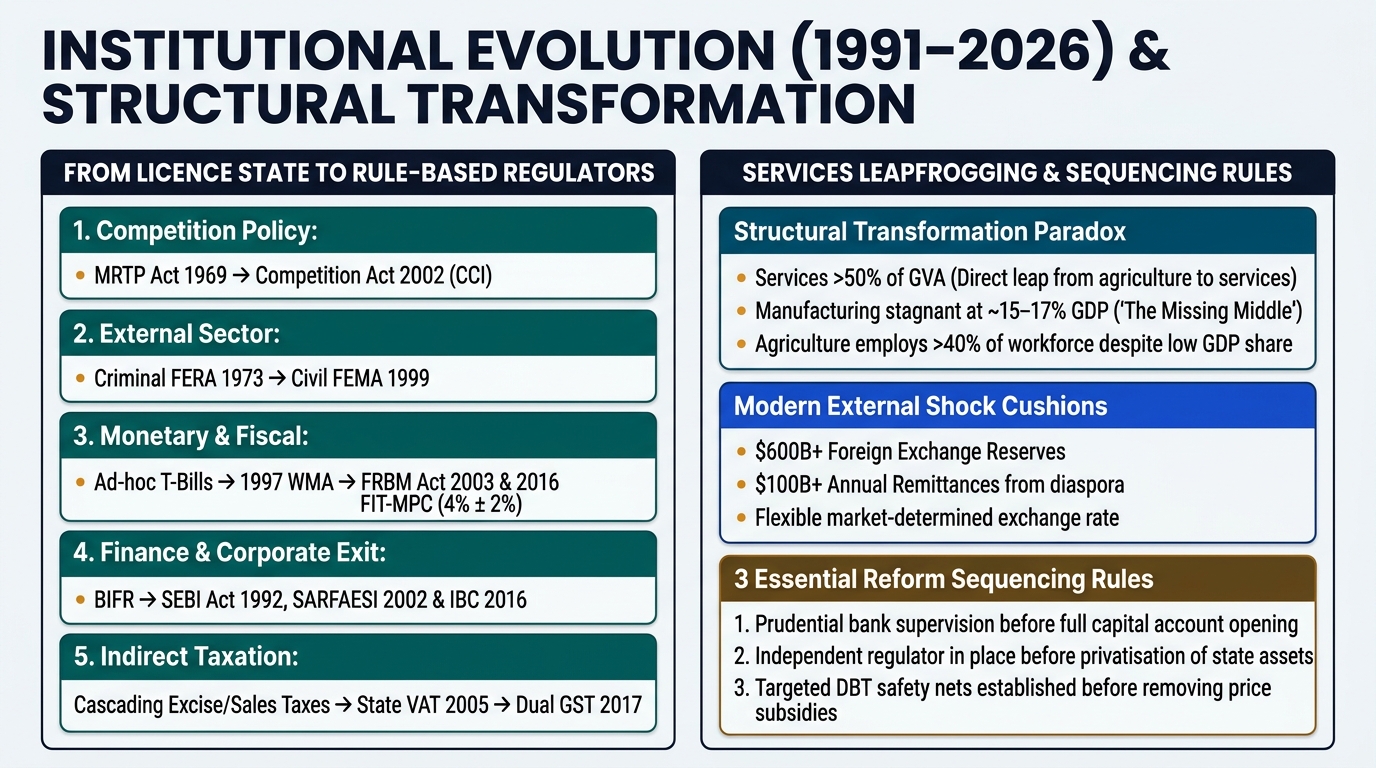
Structural reform alters the everyday rules and incentives governing how firms enter markets, price products, raise capital, adopt technology, and trade across borders, as well as how public enterprises operate and how independent regulators protect consumers and systemic stability. Unpacking the three letters of LPG reveals the concrete economic mechanisms underneath each pillar.
6.1 Liberalisation Did Not Mean Removing All Rules
Liberalisation removes unnecessary prior administrative permissions so producers, savers, and consumers can respond flexibly to market signals, innovation, and shifting demand — while retaining or strengthening rules that address safety, environmental harm, fraud, monopoly abuse, and systemic financial risk:
- New Industrial Policy (24 July 1991): Abolished industrial licensing across almost all manufacturing sectors except a short list retained for security, strategic, safety, or environmental concerns; pruned industries reserved exclusively for the public sector from 17 down to 8 (and progressively down to just atomic energy and core railway transport operations); and scrapped pre-entry MRTP asset-limit scrutiny on large business houses, shifting regulatory focus from policing firm size in advance toward curbing anti-competitive conduct (later institutionalised via the Competition Act, 2002 and the Competition Commission of India). Because delicensing alone cannot prevent a dominant firm from cornering finance, distribution networks, or digital platforms, capable competition regulation became more important, not less.
- Trade Policy Reform: Gradually dismantled quantitative import licensing on intermediate and capital goods (and later consumer goods following WTO commitments), shifted protection onto transparent tariffs, substantially lowered peak and average customs duties over the 1990s–2000s, and reduced the anti-export bias that had penalised Indian exporters.
- Financial Sector Reform Paired with Prudential Supervision: Guided by the Narasimham Committees (1991 and 1998), India progressively lowered statutory SLR/CRR pre-emptions, deregulated most interest rates, licensed new private-sector banks to spur competition, empowered the Securities and Exchange Board of India (SEBI) statutorily in 1992, and modernised equity market settlement (NSE, dematerialisation). Crucially, because banks steward public deposits and transmit systemic contagion, deregulation was paired with stricter Basel capital-adequacy norms, income-recognition and Non-Performing Asset (NPA) classification rules, and stronger RBI/SEBI supervision.
6.2 Public-Enterprise Reform Was Wider Than Privatisation
Because public enterprises served diverse strategic, infrastructural, and commercial functions, post-1991 policy deployed four distinct instruments that UPSC candidates must never conflate:
- Commercialisation & Governance Autonomy: Granting profitable PSEs clearer commercial targets, Memorandum of Understanding (MoU) accountability, and board-level investment autonomy (such as Maharatna, Navratna, and Miniratna frameworks) without selling any government equity.
- Restructuring & Turnaround / Orderly Exit: Reorganising finances, technology, product mix, or workforce (supported initially by mechanisms such as the Board for Industrial and Financial Reconstruction and the National Renewal Fund for displaced workers) where enterprises had fallen sick.
- Disinvestment (Minority Stake Sale): Selling a portion of government equity to public/institutional investors to mobilise non-debt capital receipts, broaden shareholding, and introduce market disclosure discipline while retaining majority ownership and management control with the government.
- Privatisation / Strategic Disinvestment: Transferring both a substantial ownership stake and management control to a private buyer. Economic theory stresses that ownership transfer improves welfare reliably only where genuine market competition or a capable independent regulator exists; turning an unregulated public monopoly into an unregulated private monopoly harms consumers just as severely.
6.3 Globalisation Created Both Opportunity and Exposure
Economic globalisation deepens cross-border integration of goods, services, capital, technology, data, and global value chains (GVCs) — an economic process distinct from cultural homogenisation. Post-1991 external opening followed a deliberately managed and sequenced path:
- Foreign Direct Investment (FDI) vs Foreign Portfolio Investment (FPI): India opened automatic and government-approval FDI corridors (starting with up to 51% foreign equity in 34 high-priority industries in July 1991 and expanding steadily across sectors) while permitting registered Foreign Institutional/Portfolio Investors into Indian capital markets. FDI involves a lasting management interest, physical plant/service capacity, and potential technology and supply-chain spillovers (though actual domestic capability gains depend on local workforce skills, MSME supplier linkages, and infrastructure rather than capital inflow alone). FPI purchases financial equities or bonds without management control, deepening market liquidity while remaining far quicker to reverse during global risk-off episodes (UPSC Prelims 2020).
- Sequenced Exchange-Rate & Convertibility Transition: Following the July 1991 two-step official devaluation ($\sim 18\text{--}19\%$), India avoided a reckless overnight leap into an unbuffered free float and instead executed a four-step transition recommended by the C. Rangarajan High-Level Committee on Balance of Payments:
- March 1992 — Dual-Rate LERMS (40:60 Formula): Under the interim Liberalised Exchange Rate Management System (LERMS) announced in the 1992–93 Budget, exporters and inward remitters surrendered $40\%$ of their foreign-exchange receipts at the lower RBI official rate (used to finance essential imports of crude oil, petroleum products, fertilisers, and life-saving drugs) while converting the remaining $60\%$ at the higher market-determined rate!
- March 1993 — Unified Market-Determined Exchange Rate: The 40:60 dual window was merged into a single market-determined exchange rate where day-to-day supply and demand set the rupee’s value and the RBI intervenes only to smooth disorderly volatility (managed float).
- August 1994 — Full Current Account Convertibility (IMF Article VIII): India removed exchange restrictions on current international transactions (merchandise/service trade, travel, education, medical expenses, and investment-income remittances).
- Calibrated Capital Account Convertibility (Tarapore Committees 1997 & 2006) & FEMA (1999): India joined the WTO as a founding member in 1995 and replaced criminal-law FERA (1973) with civil-law FEMA (1999), while deliberately keeping Capital Account Convertibility partial and hierarchical (favouring long-term equity FDI over short-term foreign-currency debt). As the S. S. Tarapore Committee (1997) demonstrated, full capital-account openness requires three prior domestic preconditions—fiscal consolidation ($\text{Centre’s fiscal deficit} \le 3.5\%$ of GDP), low inflation ($3\text{--}5\%$), and a resilient banking system (gross NPAs $\le 5\%$ and lower CRR)—prudence that shielded India when sudden-stop debt outflows devastated East Asian economies in 1997–98!
7. Reform Extended Far Beyond the First Package
July 1991 marked an irreversible directional pivot, not a finished blueprint. Across the 1990s, 2000s, 2010s, and 2020s, reform unfolded unevenly across sectors and tiers of India’s federal constitution. While the Union Government controlled customs tariffs, exchange rates, central banking, and corporate law, State Governments and local bodies exercised decisive constitutional authority over land records and acquisition, electricity distribution, agricultural marketing, intrastate transport, urban building approvals, water, schooling, and frontline labour administration. Consequently, removing a central industrial licence could still leave local land, power, or logistics bottlenecks intact — while pioneering policy experiments in individual states often inspired national frameworks later.
Commentators frequently group post-1990s institutional tasks under the phrase “second-generation” (or third-generation) reforms — encompassing factor-market flexibility, insolvency resolution, tax unification, judicial and administrative capacity, and human-capital delivery. Because no single statutory list defines “generations”, rigorous economic analysis organises continuing reforms by the binding economic constraint being addressed rather than by generational labels.
7.1 Institutional Evolution Matrix: From Pre-1991 Controls to Modern Market & Fiscal Architecture
To connect the July 1991 pivot with subsequent decades of legislation frequently tested in UPSC Prelims and GS Paper III, compare how six core policy domains evolved from administrative command to rule-based institutional frameworks:
| Policy Domain | Pre-1991 Control Instrument | First-Wave Reforms (1991–1999) | Systemic Institutional Consolidation (2000–Present) |
|---|---|---|---|
| 1. Industrial Entry & Competition | IDRA licensing, small-scale reservation, and MRTP Act (1969) pre-entry asset caps on large houses. | 24 July 1991 delicensing; removal of MRTP pre-entry asset clearance; pruning of public-sector reservation. | Competition Act, 2002 & CCI policing cartels, abuse of dominance, and combinations (updated via 2023 Amendment); progressive de-reservation of SSI items. |
| 2. Foreign Exchange & External Account | Fixed/basket exchange rate; quantitative import quotas; punitive FERA (1973) treating forex scarcity through criminal enforcement. | July 1991 devaluation → LERMS (1992) → Unified market rate (1993) → IMF Article VIII Current Account Convertibility (1994); WTO (1995). | FEMA, 1999 (facilitating external trade/payments under civil law); liberalised FDI routes alongside calibrated capital-account management. |
| 3. Monetary–Fiscal Coordination | Automatic monetisation of Union deficits via unlimited ad-hoc Treasury Bills; financial repression via peak SLR/CRR (~38.5% / 15%). | 1994 & 1997 RBI–Union Agreements phasing out ad-hoc T-Bills and introducing capped Ways and Means Advances (WMA); SLR/CRR cuts. | FRBM Act, 2003 (fiscal/debt rules; prohibition on primary-market RBI deficit financing save exceptional triggers) + statutory Flexible Inflation Targeting (2016 MPC: 4% ± 2%). |
| 4. Banking, Markets & Insolvency | Administered interest rates, directed credit, fragmented stock exchanges, and slow industrial sickness boards (SICA / BIFR, 1985). | Narasimham Committees I (1991) & II (1998): Basel capital adequacy, NPA norms, private bank entry; statutory SEBI Act (1992), NSE & depositories. | SARFAESI Act (2002), 2015 Asset Quality Review, and the Insolvency and Bankruptcy Code (IBC, 2016) establishing time-bound creditor-in-control resolution. |
| 5. Indirect & Direct Taxation | High, confiscatory income/corporate tax rates and cascading multi-rate Union excise, customs, and State sales taxes. | Raja Chelliah Tax Reforms Committee (1991–93): broader base, lower rates, customs tariff cuts, MODVAT expansion, and introduction of Service Tax (1994). | CENVAT & State-level VAT (2005) culminating in the constitutional Goods and Services Tax (GST, 2017) unifying India’s domestic indirect-tax market. |
| 6. Public Sector Enterprises (PSEs) | 17 core industries reserved exclusively for the public sector; departmental/ministerial micromanagement. | Reserved list cut to 8 (1991) and progressively to 2 (atomic energy & core railway operations); minority disinvestment & Navratna autonomy (1997). | Maharatna autonomy; strategic sales (e.g., Air India); New PSE Policy (2021) retaining bare-minimum presence in 4 strategic sectors while exiting non-strategic ones. |
8. How Reforms Can Improve an Economy
When structural reforms work alongside macroeconomic stability and supportive infrastructure, they raise output and living standards through clear microeconomic and macroeconomic channels:
- Allocative & Productive Efficiency: Lowering entry barriers challenges high-cost incumbents, rewards innovation, and allows capital and talent to move toward higher-value activities, while access to imported machinery, intermediates, and global technology upgrades firm productivity.
- Market Scale, Services Exports & Consumer Welfare: External opening enlarged markets for Indian pharmaceuticals, auto components, gems and jewellery, speciality chemicals, and above all IT, software, and modern business/GCC services; Indian consumers gained wider choice, higher reliability, and competitive pricing in telecoms, aviation, automobiles, and consumer durables; and India’s share in world exports, annual FDI inflows, and official foreign-exchange reserves expanded dramatically compared with 1991 (UPSC Prelims 2017).
- Methodological Caution on Attribution: Rigorous evaluation avoids attributing every post-1991 gain or setback solely to July 1991 policy announcements: global trade booms, digital technology waves, demographic shifts, monsoon variability, domestic infrastructure build-outs, and pre-1991 human-capital investments all interacted simultaneously.
9. Why Gains Can Remain Uneven
Competitive markets generate real winners, adjustment pains, and uneven spatial or social outcomes that GS Paper III answers must weigh candidly:
- Creative Destruction, Job Quality & Informality: While competitive firms expand, uncompetitive units shrink or shut down, displacing workers before comparable local jobs emerge. Facing global cost pressure, firms may adopt capital-intensive automation or hire through informal/contractual arrangements — meaning headline GDP growth does not automatically guarantee broad-based, secure formal employment.
- MSME Scale Hurdles: Micro, small, and medium enterprises face disproportionately higher costs of formal credit, logistics, quality certification, technology adoption, and regulatory compliance; removing product reservation without upgrading MSME credit and cluster infrastructure can tilt markets toward large incumbents.
- Regional Divergence & Sectoral Imbalance: Private domestic and foreign capital naturally flowed faster toward coastal, western, and southern states that already possessed stronger ports, power grids, cities, technical colleges, and administrative governance, widening inter-state per-capita income gaps. Simultaneously, while agriculture’s share of GDP fell steadily, agriculture continued employing over two-fifths of the workforce, and labour-intensive manufacturing grew more slowly than skill-intensive services.
- Inequality & Evolving External Risks: Returns to capital, urban land, and high-end skills rose faster than unskilled wages, making public investment in universal health, foundational education, and nutrition indispensable so poorer households can participate in growth. Externally, deeper integration brings exposure to imported crude-oil spikes, global monetary tightening, and concentrated supply-chain disruptions. Protecting people during transition (via portable social security, skilling, and credit access) is vital — and fundamentally different from protecting every inefficient enterprise from competition forever.
9.1 Structural Transformation Paradoxes & How External Resilience Changed Since 1991
Two macro-structural patterns stand at the heart of Economic Survey and GS Paper III evaluations of India’s post-1991 trajectory:
- Services-Led Leapfrogging & the “Missing Middle” in Manufacturing: Classical structural transformation (experienced in Western Europe and East Asia) moved output and workers sequentially from low-productivity agriculture into labour-intensive manufacturing and only later into services. Post-1991 India bypassed that sequence in output terms: high-skill services (IT-BPM, telecom, finance, Global Capability Centres) surged above half of Gross Value Added, while manufacturing’s GDP share stayed near 15–17% and industrial employment remained bifurcated between millions of tiny informal micro-enterprises and capital-intensive corporate plants (“the missing middle”). Because high-value services absorb fewer semi-skilled workers per unit of output than labour-intensive manufacturing, over two-fifths of India’s workforce remained engaged in agriculture despite agriculture generating under one-fifth of GDP — explaining why factor-market, logistics, skilling, and MSME-scaling reforms remain urgent.
- Transformed External Buffers vs New Geoeconomic Exposures: Compared with mid-1991 — when foreign-currency assets covered barely two to three weeks of imports (~USD 1.1 billion), exchange rates were rigid, and short-term debt rollover triggered an acute crunch — India built formidable external cushions: official forex reserves surpassing USD 600 billion (roughly 10–11 months of import cover), world-leading diaspora remittances (exceeding USD 100 billion annually), buoyant net services exports, a flexible market-determined exchange rate acting as an automatic shock absorber, and a low share of short-term external debt relative to reserves. Even so, external vigilance never ends: heavy reliance on imported crude oil, natural gas, edible oils, active pharmaceutical ingredients, electronics/semiconductors, and critical energy-transition minerals means geopolitical fragmentation, tariff shocks, or global monetary tightening still transmit rapidly into domestic inflation and growth.
10. The State Changed Its Work; It Did Not Vanish
A pervasive misconception portrays 1991 as a simple retreat of the state in favour of unregulated markets. In reality, while markets excel at coordinating dispersed price signals and rewarding entrepreneurial innovation, left alone they also generate monopolies, cartels, environmental externalities, information asymmetries, unsafe drugs/foods, financial panics, and exclusion of the poor.
Post-1991 India therefore shifted the state’s primary role from pervasive prior command and case-by-case licensing toward rule-setting, independent regulation, public-good provision, and capability building. Independent statutory regulators — such as RBI, SEBI, TRAI (telecom), IRDAI (insurance), PFRDA (pensions), CCI (competition), and CERC/SERCs (electricity) — were created or strengthened to referee markets neutrally, even where public and private operators compete side by side. Simultaneously, public investment remained irreplaceable in highways, railways, rural roads, digital public infrastructure, basic research, public health, schooling, and social safety nets. Paradoxically, effective market regulation and long-term public-private partnership (PPP) contract management require higher technical and institutional state capacity than stamping an administrative licence ever did. The real policy question is never “state versus market” in the abstract, but which institution performs each function best, under what incentives, and with what accountability.
11. Sequencing, Complements, and Safety Nets Shape Results
Why can the exact same legal reform ignite dynamic competition in one state or sector yet stall or backfire in another? Because rules work through complementary institutions and careful sequencing:
- Complementary Enablers: Abolishing factory licensing produces new entrants only where entrepreneurs can also secure reliable electricity, clear land titles, affordable institutional credit, skilled workers, efficient ports, and timely contract enforcement in courts.
- Prudent Sequencing Rules: Opening domestic banks or capital accounts before building prudential supervision invites financial crises; privatising a natural network monopoly (ports, airports, power distribution) before establishing an independent tariff and access regulator merely creates a private monopoly; rationalising consumer subsidies before putting targeted alternatives or direct income transfers in place inflicts severe household distress. Conversely, waiting passively until every institutional condition is 100% perfect can entrench vested interests indefinitely — requiring pragmatic, phased execution backed by continuous empirical feedback.
12. The Continuing Reform Agenda
Because technology, demographics, geopolitics, and climate constraints keep evolving, India’s continuing reform agenda spans seven interconnected problem domains rather than a static checklist:
- Product & Factor Markets: Streamlining land titling/leasing, modernising labour codes alongside worker security, deepening corporate bond and MSME credit markets, and ensuring swift commercial dispute and insolvency resolution (such as strengthening the Insolvency and Bankruptcy Code ecosystem) so capital and labour can enter, scale, and exit smoothly.
- Physical & Digital Infrastructure and Logistics: Reducing farm-to-port and factory-to-market logistics costs through multimodal connectivity (PM GatiShakti, Dedicated Freight Corridors, ports) and interoperable Digital Public Infrastructure.
- Human Capital & Employability: Raising learning outcomes in schools, industry-aligned vocational skilling, preventive and primary healthcare, nutrition, and female labour-force participation.
- Resilient Financial Intermediation & Simple, Fair Taxation: Sustaining clean bank/NBFC balance sheets while simplifying direct and indirect tax compliance (including rationalising GST slabs/processes) without eroding public revenue buoyancy.
- State, Regulatory & Judicial Capacity: Strengthening civil-service specialisation, transparent public procurement, independent data systems, evidence-based regulatory impact assessment, and faster contract enforcement.
- Cooperative & Municipal Federalism: Aligning Union frameworks with State implementation and empowering financially viable Urban Local Bodies and Panchayats that manage cities and industrial corridors on the ground.
- Portable Social Protection & Just Green Transition: Ensuring migrant and gig/informal workers carry portable welfare protections while decarbonising power, industry, and transport without jeopardising energy security or vulnerable livelihoods.
13. How to Judge Any Economic Reform
Whether analysing a historic 1991 measure or a brand-new policy proposal in UPSC Mains GS Paper III or the Essay paper, evaluate every reform through four disciplined steps:
- Step 1 — Diagnosis: Exactly what market failure (monopoly, externality, asymmetric information, missing public good) or government/regulatory failure (rent-seeking licence, price distortion, weak state capacity) is causing the observed problem?
- Step 2 — Mechanism & Complements: How will changing the rule alter concrete incentives of firms, workers, savers, lenders, and officials — and are complementary inputs (power, logistics, credit, competition law) in place for that mechanism to operate?
- Step 3 — Transition & Distributional Incidence: Who bears the immediate adjustment cost, who captures early gains, and what retraining, credit upgrading, or social safety nets help vulnerable workers, MSMEs, and lagging regions adapt without freezing inefficient structures permanently?
- Step 4 — Institutional Capacity, Resilience & Feedback: Do regulators possess technical independence and accountability to enforce the new regime, do fiscal and external buffers absorb shocks, and what measurable indicators will trigger mid-course correction?
That is the enduring lesson of 1991: India overcame an acute foreign-exchange liquidity emergency through stabilisation and shifted away from pervasive prior administrative control toward market competition and global engagement — discovering at every stage that dynamic markets require stronger, smarter public institutions, physical and human capital complements, and inclusive transition support.
13.1 Concrete Worked Examples: 1991 Reserve & Devaluation Math, LERMS 40:60 & Capital-Flow Resilience, and Applying the 4-Step Reform Test
To master how macroeconomic accounting, exchange-rate regimes, and structural reform design operate in concrete numerical and policy scenarios, step through these three worked examples:
Scenario: Using the actual macroeconomic magnitudes of 1990–91, trace why India faced an acute foreign-exchange liquidity emergency without defaulting, and how the July 1991 stabilisation package restored breathing room:
- Step 1 — Twin-Deficit & Rollover Arithmetic (1990–91):
- By 1990–91, the Centre’s Gross Fiscal Deficit stood at $\sim 7.8\text{--}8.4\%$ of GDP, while the economy-wide Current Account Deficit (CAD) widened to $\sim 3.0\%$ of GDP ($\sim\text{USD } 9.7\text{ billion}$) after the August 1990 Gulf Crisis doubled crude-oil prices from $\sim\text{USD } 15\text{/bbl}$ to over $\text{USD } 30\text{/bbl}$.
- India’s monthly merchandise import bill averaged $\sim\text{USD } 2.0\text{ billion per month}$ ($\sim\text{USD } 500\text{ million per week}$). When international credit ratings were downgraded in early 1991, foreign banks refused to roll over short-term commercial credit and Non-Resident Indians withdrew roughly $\text{USD } 300\text{ million per month}$ from foreign-currency deposits (FCNR accounts).
- By June 1991, RBI’s usable Foreign Currency Assets (FCA) plunged to $\sim\text{USD } 1.1\text{ billion}$: $$\text{Import Cover in Weeks} = \frac{\text{USD } 1,100\text{ million}}{\text{USD } 500\text{ million/week}} \approx 2.2\text{ weeks (barely 15 days of essential imports!)}$$
- Step 2 — Emergency Gold Bridge Liquidity ($\sim\text{USD } 600\text{ Million}$):
- To prevent a sovereign default on maturing debt, India leased $\sim 20\text{ tonnes}$ of confiscated gold via SBI to Union Bank of Switzerland ($\sim\text{USD } 200\text{ million}$) and physically airlifted $\sim 46.9\text{ tonnes}$ of RBI monetary gold to the Bank of England and Bank of Japan in four tranches during July 1991 to raise $\sim\text{USD } 405\text{ million}$—buying critical weeks until IMF Stand-By/CCFF disbursements arrived, after which the RBI redeemed its pledged gold later in 1991!
- Step 3 — Two-Step Official Devaluation (1 July & 3 July 1991, Codeword “Hop, Skip and Jump”):
- On 1 July 1991, the RBI adjusted the rupee downward by $\sim 9\%$, and on 3 July 1991 by a further $\sim 11\%$, shifting the dollar rate from roughly ₹21.2 per USD to ₹25.8 per USD (an official devaluation of $\sim 18\text{--}19\%$ in foreign-currency terms / $\sim 21.7\%$ rise in rupee price of the dollar), allowing the Commerce Ministry to abolish budgetary export subsidies (Cash Compensatory Support) the very same day, reducing the fiscal deficit simultaneously!
Scenario A (LERMS 40:60 Math): In April 1992 under LERMS, an Indian textile exporter earns $\text{USD } 100,000$. Suppose the RBI official rate is ₹25.89/USD and the open market rate is ₹30.50/USD. How many rupees does the exporter receive, and why did the 40:60 split act as an implicit tax on exports until March 1993?
- 40% Surrendered at Official Rate: $\text{USD } 40,000 \times ₹25.89 = ₹10,35,600$.
- 60% Converted at Market Rate: $\text{USD } 60,000 \times ₹30.50 = ₹18,30,000$.
- Total Realisation: $₹28,65,600$ (an effective blended exchange rate of ₹28.66/USD, which is ₹1.84/USD lower than the full market value of ₹30.50/USD). When India unified the exchange rate in March 1993, the exporter received 100% at the market rate ($₹30,50,000$), eliminating the implicit export tax while oil imports moved onto the market rate!
Scenario B (FDI vs. FPI vs. Short-Term ECB During a Global Shock): Suppose three firms each bring $\text{USD } 100\text{ million}$ into India via (1) a greenfield auto-component factory (FDI), (2) secondary-market equity purchases by a foreign fund (FPI), and (3) a 6-month dollar loan from a foreign bank (Short-Term ECB). When a global rate hike hits and the rupee depreciates by 10%: the Short-Term ECB demands fixed dollar repayment of $\text{USD } 100\text{ million}$ plus interest immediately (rising 10% in rupee cost and threatening a rollover crunch); the FPI investor can sell shares overnight on the stock exchange (though the falling share price and weaker rupee automatically shrink the dollar amount they take out, sharing valuation risk!); and the FDI factory remains physically anchored in India, continuing production and exports without any fixed debt-service outflow (UPSC Prelims 2020).
Scenario: Why do Indian manufacturing MSMEs pay some of the world’s highest industrial electricity tariffs despite India achieving near-universal grid generation capacity? Apply Section 13’s 4-step diagnostic framework:
- Step 1 — Diagnosis (Government + Market Failure): State power distribution companies (DISCOMs) face uncompensated agricultural/retail tariff subsidies, billing/technical losses (AT&C losses), and delayed departmental payments. To cover the gap, State regulators impose heavy cross-subsidy surcharges on industrial and commercial users—acting as an input-cost tax that hurts Indian factory exports and forces factories to run costly diesel generators.
- Step 2 — Mechanism & Complements: Simply delicensing electricity generation (accomplished under the Electricity Act, 2003) could not fix retail distribution without complementary smart prepaid metering, feeder segregation (PM-KUSUM solarising farm feeders), timely direct budget subsidy transfers, and independent State Electricity Regulatory Commissions (SERCs) enforcing cost-reflective tariffs.
- Step 3 — Transition & Distributional Support: Rather than cutting off small farmers abruptly, substituting daytime solar feeder power and transparent direct-benefit accounting protects farm livelihoods while allowing industrial cross-subsidies to come down gradually.
- Step 4 — Institutional & Federal Capacity: Because electricity is a Concurrent List (Seventh Schedule) subject, sustained reform requires cooperative Union–State compacts (linking extra state borrowing ceilings and Revamped Distribution Sector Scheme grants to verified reductions in AT&C losses and ACS-ARR gaps).
UPSC CSE Prelims Previous Year Questions (PYQs)
India’s economic liberalisation in 1991 was followed by which of the following trends in the Indian economy?
1. Share of agriculture in GDP increased enormously.
2. Share of India’s exports in world trade increased.
3. FDI inflows increased.
4. India’s foreign exchange reserves increased enormously.
Select the correct answer using the code given below:
(a) 1 and 4 only (b) 2, 3 and 4 only (c) 2 and 3 only (d) 1, 2, 3 and 4
Explanation: Following the 1991 reforms, agriculture’s percentage share in India’s GDP continued its structural decline (falling from roughly 29% in 1990–91 to below 18–19% over subsequent decades as services expanded rapidly), eliminating Statement 1 immediately. Meanwhile, India’s share in global merchandise and commercial services exports rose substantially (Statement 2), annual FDI inflows expanded manifold (Statement 3), and official foreign-exchange reserves grew from roughly USD 1.1 billion in mid-1991 to hundreds of billions of dollars (Statement 4).
(a) Curbing imports of non-essential goods and promoting exports
(b) Encouraging Indian borrowers to issue rupee-denominated Masala Bonds
(c) Easing conditions relating to external commercial borrowing
(d) Following an expansionary monetary policy
Explanation: Just as stabilisation in 1991 required tighter monetary and credit discipline to curb excess aggregate demand, inflation, and capital outflows, an expansionary monetary policy (cutting policy interest rates and injecting rupee liquidity) lowers domestic interest yields, raises import demand, and accelerates currency depreciation rather than defending the rupee.
1. If the inflation is too high, Reserve Bank of India (RBI) is likely to buy government securities.
2. If the rupee is rapidly depreciating, RBI is likely to sell dollars in the market.
3. If interest rates in the USA or European Union were to fall, that is likely to induce RBI to buy dollars.
Which of the statements given above are correct?
(a) 1 and 2 only (b) 2 and 3 only (c) 1 and 3 only (d) 1, 2 and 3
Explanation: Under India’s post-1993 market-determined managed exchange system, when the rupee depreciates sharply, RBI sells dollars from its foreign-exchange reserves to supply foreign currency and curb disorderly volatility (Statement 2 correct). Lower US/EU interest rates spur foreign capital inflows into India, appreciating the rupee and inducing RBI to buy dollars to build reserves and prevent excessive appreciation (Statement 3 correct). High inflation calls for RBI selling (not buying) G-Secs to absorb rupee liquidity (Statement 1 incorrect).
(a) It is the investment through capital instruments essentially in a listed company.
(b) It is a largely non-debt creating capital flow.
(c) It is the investment which involves debt-servicing.
(d) It is the investment made by foreign institutional investors in the Government securities.
Explanation: One of the central lessons of India’s 1991 BoP crisis was the danger of financing current-account deficits overwhelmingly via short-term debt-creating commercial borrowings and volatile deposits. FDI brings equity capital with lasting management interest and does not create fixed contractual sovereign/corporate external debt-servicing obligations in the way external commercial loans do.
Practice MCQs for UPSC Prelims
1. Macroeconomic stabilisation focuses on containing immediate balance-of-payments and inflationary pressures through fiscal restraint, monetary tightening, and exchange-rate adjustment.
2. Structural reform alters underlying institutional rules and incentives governing industrial entry, trade openness, financial allocation, and public enterprises to raise long-run productivity.
3. Successful short-run stabilisation automatically eliminates domestic entry barriers and improves industrial competitiveness without separate regulatory reforms.
Which of the statements given above are correct?
(a) 1 and 2 only (b) 2 and 3 only (c) 1 and 3 only (d) 1, 2 and 3
1. External Debt : Stock variable measured at a point in time
2. External Debt Service : Flow variable of principal and interest falling due during a period
3. Official Foreign-Exchange Reserves : Flow receipt inside the Union Government’s Revenue Budget
Select the correct answer:
(a) 1 and 2 only (b) 2 and 3 only (c) 1 and 3 only (d) 1, 2 and 3
(a) A fiscal deficit and a current account deficit are mathematically identical in every open economy.
(b) A BoP crisis occurs only when the double-entry BoP accounting table fails to sum to zero.
(c) A fiscal deficit can widen the CAD by raising domestic demand and imports, yet private saving and investment behaviour also independently shape the CAD; a BoP crisis arises when normal voluntary external financing dries up.
(d) India’s 1991 crisis occurred despite zero external debt service falling due in 1990–91.
1. Two-step official devaluation of the Indian rupee
2. Introduction of the dual-rate Liberalised Exchange Rate Management System (LERMS)
3. Transition to a unified market-determined exchange-rate system
4. Acceptance of IMF Article VIII obligations for Current Account Convertibility
Select the correct chronological code:
(a) 1 – 2 – 3 – 4 (b) 2 – 1 – 3 – 4 (c) 1 – 3 – 2 – 4 (d) 1 – 2 – 4 – 3
1. Pledging RBI monetary gold abroad served as collateralised short-term bridge liquidity to prevent default and was later redeemed, rather than permanently solving structural fiscal or trade weaknesses.
2. While IMF financing primarily addressed immediate balance-of-payments and macroeconomic stabilisation, World Bank lending supported structural sector adjustments.
Which of the statements given above is/are correct?
(a) 1 only (b) 2 only (c) Both 1 and 2 (d) Neither 1 nor 2
(a) All environmental, safety, and strategic licensing rules across every sector were abolished without exception.
(b) Pre-entry asset-limit restrictions on large business houses under the MRTP regime were removed, shifting policy emphasis toward regulating monopolistic and anti-competitive conduct.
(c) Every Central Public Sector Enterprise was privatised within twelve months.
(d) Quantitative import restrictions on all consumer goods were abolished on 24 July 1991 itself.
(a) Disinvestment always transfers 100% ownership and management control to foreign companies, whereas privatisation retains majority government voting rights.
(b) Minority disinvestment sells part of the government’s equity shareholding while retaining majority ownership and management control with the state, whereas privatisation/strategic sale transfers management control and substantial ownership to private buyers.
(c) Granting Maharatna operational autonomy to a PSU is legally classified as complete privatisation.
(d) Transferring a natural monopoly to an unregulated private monopolist guarantees consumer welfare gains even without competition or regulatory oversight.
(a) Because deregulating banks without prudential supervision or privatising network monopolies without independent regulators can replace administrative failure with financial instability or private monopoly abuse.
(b) Because constitutional federalism gives the Union Government exclusive jurisdiction over land records, intrastate power distribution, and municipal services.
(c) Because removing industrial licences guarantees identical per-capita industrial growth across every district regardless of roads, power, or workforce skills.
(d) Because social safety nets require permanently banning all domestic or foreign competition.
UPSC Mains Practice Questions (GS Paper III — Indian Economy)
“India’s 1991 economic reforms did not represent the withdrawal of the state, but rather a demanding transformation of what the state must do.” Examine this statement with reference to macroeconomic stabilisation, regulatory institutions, public investment, and uneven regional and employment outcomes since 1991.
Approach Hints: Contrast pre-1991 prior command (licensing, MRTP pre-entry caps, QRs, financial repression) with post-1991 rule-setting and refereeing (RBI, SEBI, CCI, TRAI, CERC); highlight why regulating market power and PPP contracts requires higher state capacity; balance export/GDP/reserve gains against regional divergence, MSME hurdles, and informal employment; conclude with public investment in infrastructure, health/education, and portable safety nets.
Distinguish between macroeconomic stabilisation and structural reform in India’s response to the 1991 balance-of-payments crisis. Why do factor-market bottlenecks, federal coordination, and reform sequencing remain central to India’s continuing reform agenda?
Approach Hints: Separate short-run emergency stabilisation (fiscal consolidation, July 1991 devaluation, gold/IMF bridge liquidity) from long-run supply-side LPG reforms; explain why product-market delicensing outpaced factor-market reforms (land, labour, power, logistics, skilling, contract enforcement) across Union, State, and municipal tiers; illustrate sequencing principles and the four-step diagnostic framework for judging future reforms.
Frequently Asked Questions (FAQs)
14. Primary Official Reports, Committees & Statutory Sources
- Foundational 1991 Policy Documents: Ministry of Finance, Union Budget Speech 1991–92 (Dr Manmohan Singh, 24 July 1991) and Economic Survey 1990–91 & 1991–92; Ministry of Industry, Statement on Industrial Policy (24 July 1991).
- Landmark Reserve Bank & Ministry of Finance Committee Reports: High-Level Committee on Balance of Payments (Chairman: Dr C. Rangarajan, 1993); Committee on the Financial System (Narasimham Committee I, 1991) and Committee on Banking Sector Reforms (Narasimham Committee II, 1998); Tax Reforms Committee (Chairman: Prof. Raja J. Chelliah, 1991–93); and Committee on Capital Account Convertibility (Tarapore Committee I, 1997 & II, 2006).
- Core Post-1991 Statutes & Agreements: SEBI Act, 1992; RBI–Government Supplemental Agreements on Ad-hoc Treasury Bills & WMA (1994 & 1997); Foreign Exchange Management Act (FEMA), 1999; Competition Act, 2002; Fiscal Responsibility and Budget Management (FRBM) Act, 2003; Insolvency and Bankruptcy Code (IBC), 2016; Reserve Bank of India Act Amendment (Flexible Inflation Targeting MPC), 2016; and Constitution (One Hundred and First Amendment) Act, 2016 (GST).