

Demand, Supply, Markets and the Role of Prices
A complete UPSC Prelims and GS Paper III guide to demand and supply curves, movements vs shifts, Giffen vs normal/inferior goods, market equilibrium, price/income/cross elasticity, total revenue tests, binding price ceilings and floors, and statutory vs economic tax incidence.
Imagine an office district served by several small neighbourhood kitchens preparing hot lunch boxes. Every office worker makes an independent daily choice within a limited budget: at a modest price many buy a box; at a steep price several bring tiffins from home or switch to cheaper snacks. Separately, each kitchen weighs its vegetables, cooking gas, staff hours, and stove capacity: at a very low selling price preparing dozens of extra boxes barely covers additional cost and effort, whereas a higher price makes overtime and spare-burner output worthwhile.
When those separate plans meet in a market (whether a street lane, a wholesale mandi, or a smartphone app), posted prices expose mismatches immediately. If a low price leads workers to seek 80 boxes while kitchens offer only 40, queues and unfilled orders create upward pressure on price and preparation. If a high price leads kitchens to prepare 80 boxes while workers buy only 40, unsold food pushes sellers to trim prices or tomorrow’s batch. A price at which planned purchases equal planned sales brings decentralised decisions into line — yet that compatibility never proves by itself that every hungry person could afford lunch, that no seller exercised unfair power, or that society achieved its most equitable outcome.
1. Demand Begins With a Buyer’s Plan
In economics, demand describes how much of a good or service buyers are willing and able to purchase across different possible prices during a stated time period, while all other relevant influences remain unchanged (ceteris paribus — “other things being equal”). Every clause of that definition prevents an exam trap:
- Willingness + Purchasing Ability: Mere desire without ability to pay is not effective market demand; conversely, ability to pay without willingness to buy also generates zero demand.
- Demand (Entire Relationship) vs Quantity Demanded (Single Point): Quantity demanded refers to the specific amount planned at one stated price (e.g., 60 boxes at ₹40); demand refers to the entire schedule or curve relating every possible price to its planned purchase quantity.
- Explicit Time Window & Ceteris Paribus Discipline: Buying 40 boxes in one afternoon differs sharply from buying 40 boxes in a month, and holding income, tastes, and rival meal prices temporarily constant isolates the pure effect of the lunch box’s own price.
1.1 Schedule, Curve, the Law of Demand & the Giffen Special Case
A demand schedule tabulates planned purchases at alternative prices, and a demand curve plots price on the vertical axis against quantity on the horizontal axis. For almost all ordinary goods, buyers plan to purchase less when own price rises and more when own price falls, ceteris paribus — the Law of Demand, producing a downward-sloping demand curve for two reinforcing reasons:
- Substitution Effect: A lower lunch-box price makes it cheaper relative to café meals or snacks, inducing buyers to switch towards it.
- Real Purchasing-Power (Income) Effect: A lower price stretches the buyer’s existing money budget further, enabling broader or repeat purchases.
Two subtleties frequently tested in UPSC Prelims keep the Law of Demand precise:
- Expectation Shifts Do Not Refute the Law: If workers hear that lunch prices will jump sharply tomorrow and rush to buy more today even as today’s price ticks up, an outside determinant (future price expectations) shifted the entire demand curve — that is not an upward own-price movement under ceteris paribus.
- The Rare Giffen-Good Case: For an impoverished household spending a massive share of its budget on an inferior staple (say, coarse grain or potatoes), a sharp rise in that staple’s price shrinks real purchasing power so severely that the household can no longer afford any meat, vegetables, or milk — forcing it to consume more of the Inferior staple just to meet survival calories! A Giffen good must therefore be an inferior good whose negative income effect outweighs its substitution effect.
1.2 Movement Along Demand vs Shift of the Demand Curve
Separating own-price movements from curve-shifters is the single most important discipline in price theory:
- Change in Quantity Demanded (Movement Along the Same Curve): Triggered solely by a change in the good’s own price — a fall in own price causes an extension (downward-rightward movement along the curve); a rise in own price causes a contraction (upward-leftward movement along the curve).
- Change in Demand (Shift of the Entire Curve): Triggered when any non-own-price determinant changes how much buyers want at every possible price (shifting the curve rightward for an increase in demand, or leftward for a decrease):
- Buyer Income (Normal vs Inferior Goods): Higher income shifts demand rightward for a normal good, but leftward for an inferior good as consumers upgrade to preferred alternatives (note: “inferior” describes income response, not defective quality, and the same food item can be normal at very low incomes yet inferior at higher incomes!).
- Prices of Related Goods (Substitutes vs Complements): If the price of a rival substitute (café sandwich) rises, lunch-box demand shifts rightward; if the price of a joint complement (paid delivery fee or accompaniment) rises, demand for delivery meals shifts leftward.
- Preferences, Information, Expectations & Buyer Count: Health endorsements, expected future price rises, or new offices opening nearby shift market demand rightward even when today’s menu price has not moved.
2. Supply Begins With a Seller’s Plan
Supply describes how much of a good sellers are willing and able to offer for sale at different possible prices during a stated period, ceteris paribus, whereas quantity supplied denotes the amount offered at one specific price. Notice that supply is not identical to physical stock in a godown: a merchant holding 500 bags of grain may offer only 150 bags at today’s low price, while a willing kitchen cannot supply 300 hot lunches if its stove capacity maxes out at 100.
Under the Law of Supply, higher own prices typically induce larger quantities supplied (an upward-sloping supply curve) because higher unit revenue covers dearer overtime labour, intensive equipment use, and rising marginal costs. However, time horizon and market structure shape supply slopes decisively: during a one-hour lunch rush or right after harvest of a perishable crop, supply may be nearly vertical (fixed quantity); over a month kitchens add shifts; over a year new kitchens enter, making long-run supply far more responsive. (In specialised cases like individual labour supply at very high wages, a worker may even trade extra hours for leisure, producing a backward-bending segment.)
2.1 Movement Along Supply vs Shift of the Supply Curve
A change in the lunch box’s own selling price moves sellers along their existing supply curve (changing quantity supplied). By contrast, the entire supply curve shifts (rightward = more offered at every price; leftward = less offered at every price) whenever an underlying production condition changes:
- Input Prices: Dearer vegetables, cooking gas, electricity, or wages trim net margins at every selling price, shifting supply leftward.
- Technology & Organisation: Energy-efficient ovens or better kitchen workflow allow more output from identical inputs, shifting supply rightward.
- Prices of Alternative Outputs Using Shared Inputs: If morning/corporate snack packs suddenly become much more lucrative in the same kitchen space, resources pivot away from lunch boxes, shifting lunch-box supply leftward.
- Expectations, Weather, Per-Unit Taxes/Subsidies & Seller Entry: Expecting higher future prices on storable grain (withholding stock today), monsoon crop damage, or a new per-unit sales tax shifts current supply leftward, whereas production subsidies or entry of new kitchens shifts market supply rightward.
3. The Two Plans Meet in a Market: Equilibrium, Shortage and Surplus
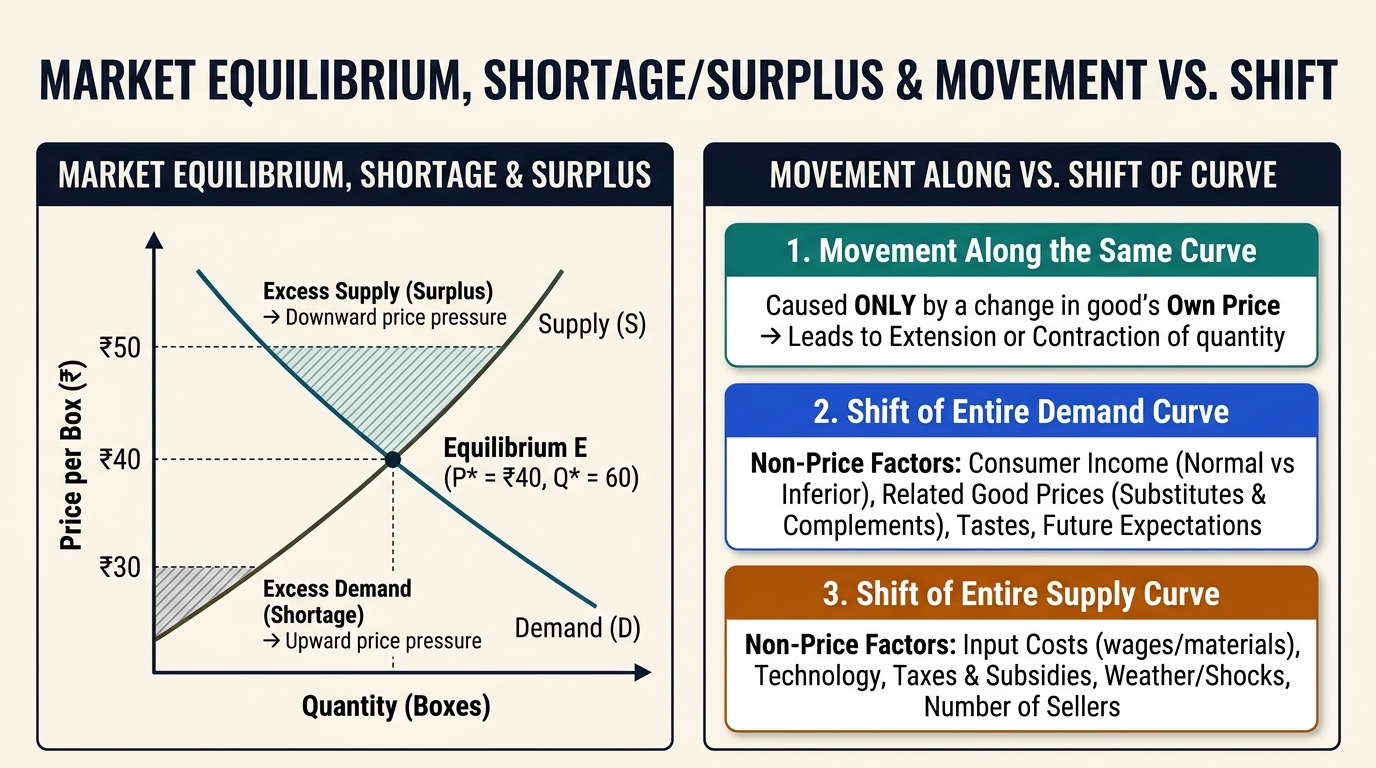
Summing individual buyer quantities horizontally at each common price yields market demand; summing individual seller quantities horizontally yields market supply (for identical product quality, location, and period). Consider the illustrative lunch-box market schedule below:
| Price per Box (₹) | Market Quantity Demanded (Boxes) | Market Quantity Supplied (Boxes) | Market State & Gap | Competitive Price Pressure |
|---|---|---|---|---|
| ₹20 | 100 | 20 | Excess Demand (Shortage) = 80 | Strong upward pressure on price |
| ₹30 | 80 | 40 | Excess Demand (Shortage) = 40 | Upward pressure on price |
| ₹40 | 60 | 60 | Equilibrium (Plans Match: 0 Gap) | No net tendency to change |
| ₹50 | 40 | 80 | Excess Supply (Surplus) = 40 | Downward pressure on price |
| ₹60 | 20 | 100 | Excess Supply (Surplus) = 80 | Strong downward pressure on price |
Two conceptual distinctions here are foundational for UPSC Prelims:
- Shortage ≠ Scarcity: Scarcity is the permanent economic condition that finite resources have competing uses even at equilibrium; a shortage (excess demand) exists only when the prevailing price lies below market-clearing equilibrium (such as ₹30, where 80 demanded > 40 supplied).
- Pressure, Friction & Non-Price Adjustments: In flexible competitive markets, shortages push prices up (expanding quantity supplied and contracting quantity demanded toward ₹40) while surpluses push prices down. In real life, monthly fixed-price contracts, capacity lags, regulations, or seller market power can slow price adjustment — causing markets to adjust simultaneously via non-price channels such as queues, waiting times, smaller portion sizes, purchase quotas, or (under surpluses) discounts, free delivery, storage, and quality upgrades.
4. Shifts Change the Equilibrium Price and Quantity
Rather than memorising mechanical arrows, trace every market shock in three logical steps: (1) Which curve(s) shifted and in which direction? (2) At the old equilibrium price, did a shortage or surplus emerge? (3) How do price and traded quantity adjust to clear that gap?
| Market Shock / Shift | Gap Created at Initial Price | New Equilibrium Price (P*) | New Equilibrium Quantity (Q*) |
|---|---|---|---|
| 1. Demand Increases (shifts right; Supply unchanged) | Shortage at old price | Rises (↑) | Rises (↑) |
| 2. Demand Decreases (shifts left; Supply unchanged) | Surplus at old price | Falls (↓) | Falls (↓) |
| 3. Supply Increases (shifts right; Demand unchanged) | Surplus at old price | Falls (↓) | Rises (↑) |
| 4. Supply Decreases (shifts left; Demand unchanged) | Shortage at old price | Rises (↑) | Falls (↓) |
| 5. Both Demand ↑ AND Supply ↑ Simultaneously | Depends on relative shift size | Indeterminate (rises if ΔD > ΔS; falls if ΔS > ΔD; flat if equal) | Unambiguously Rises (↑) |
| 6. Demand ↑ While Supply ↓ Simultaneously | Reinforcing shortage at old price | Unambiguously Rises (↑) | Indeterminate (depends on relative shift size) |
5. Elasticity Asks How Large the Response Is
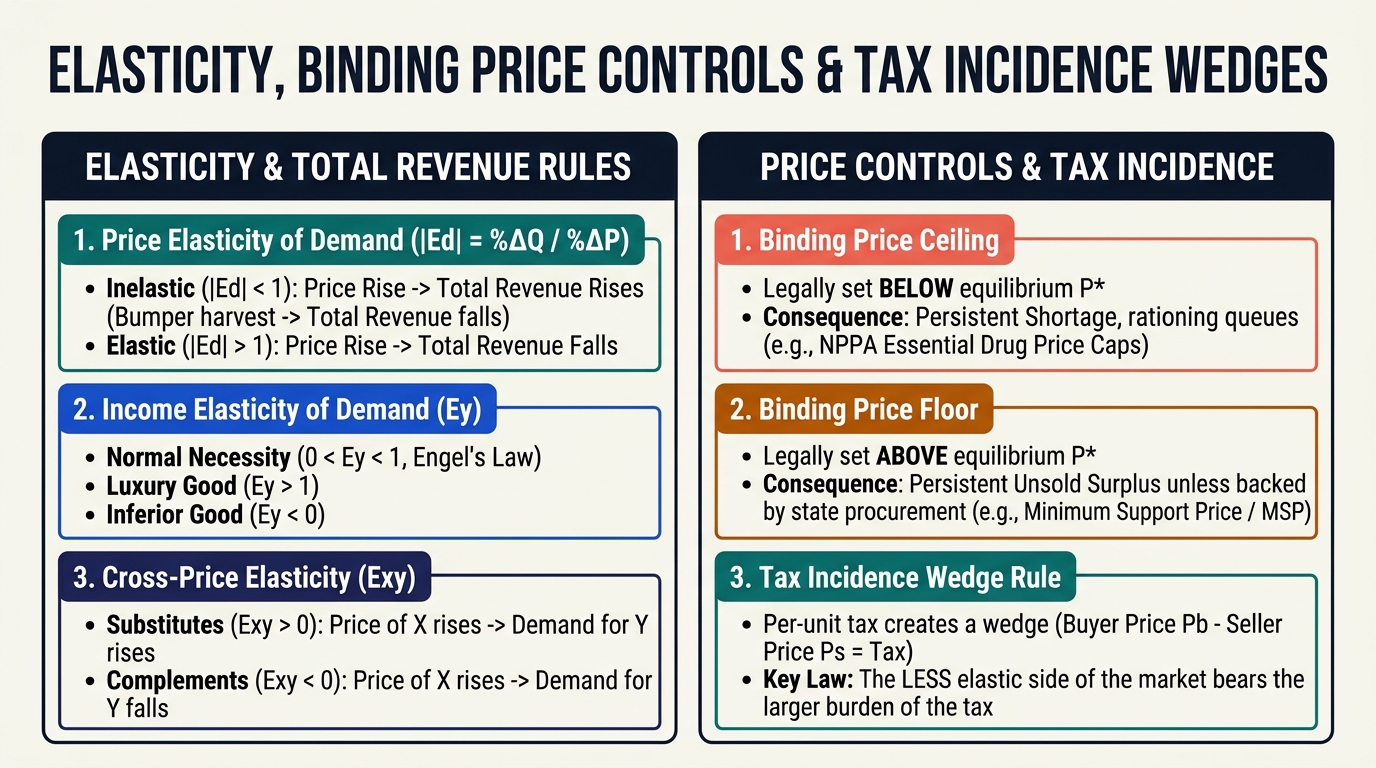
While the laws of demand and supply tell us the direction of response, elasticity measures its proportionate magnitude in unit-free percentage terms:
- Price Elasticity of Demand (|Ed|): Defined as percentage change in quantity demanded ÷ percentage change in own price. If an 8% price rise reduces lunch-box purchases by 4%, absolute elasticity is 4 ÷ 8 = 0.5 — inelastic (< 1) because quantity changed proportionately less than price. When percentage quantity response exceeds percentage price change, demand is elastic (> 1); when equal, it is unit elastic (= 1). Demand is more elastic when close substitutes exist (one brand of tiffin vs food as a whole), when the item takes a big share of the household budget, when purchase can be postponed, and over longer adjustment horizons; bare necessities like salt or emergency medicines have highly inelastic short-run demand.
- Price Elasticity of Supply (Es): Defined as percentage change in quantity supplied ÷ percentage change in own price. Supply is much more elastic when producers hold spare capacity, storable inventories, mobile inputs, and longer adjustment time, and highly inelastic when output is perishable, capacity-maxed, or tied to a slow agricultural harvest cycle.
- Point Elasticity vs. Arc (Midpoint) Elasticity & Five Benchmark Degrees ($|E_d| \ne \text{Slope}$): Because slope ($\Delta P / \Delta Q$) depends on arbitrary physical and currency units, economists compute elasticity using either the Point Formula or (for discrete jumps between two prices $P_1, P_2$) the base-independent Arc (Midpoint) Formula: $$\text{Point } |E_d| = \left|\frac{\Delta Q}{\Delta P}\right| \cdot \frac{P}{Q}, \qquad \text{Arc } |E_d| = \frac{|Q_2 - Q_1| / [(Q_1 + Q_2)/2]}{|P_2 - P_1| / [(P_1 + P_2)/2]}$$ Even when $\Delta Q / \Delta P$ is constant along a straight-line demand curve, the ratio $P/Q$ changes at every point — spanning all five benchmark degrees of elasticity: (1) Perfectly Inelastic ($|E_d| = 0$): vertical demand line (quantity unchanged at any price, e.g., acute life-saving insulin); (2) Relatively Inelastic ($0 < |E_d| < 1$): $\% \Delta Q < \% \Delta P$ (staple foods, salt); (3) Unit Elastic ($|E_d| = 1$): $\% \Delta Q = \% \Delta P$ (midpoint of a linear demand curve, or a rectangular hyperbola where $P \times Q = \text{constant}$); (4) Relatively Elastic ($1 < |E_d| < \infty$): $\% \Delta Q > \% \Delta P$ (specific brands with close substitutes); and (5) Perfectly Elastic ($|E_d| = \infty$): horizontal demand line (any price rise above market level drops sales to zero).
- The Total Revenue / Total Spending Test (TR = P × Q): Along a fixed demand curve, raising own price pushes P up while pulling Q down. When demand is inelastic (|Ed| < 1), the smaller percentage drop in Q means a price rise increases total spending/revenue; when demand is elastic (|Ed| > 1), the larger percentage drop in Q means a price rise reduces total spending/revenue!
5.1 Income Elasticity, Cross-Price Elasticity, Engel’s Law & Veblen vs Giffen Goods
Alongside own-price elasticity, UPSC Prelims tests how signed elasticities classify goods across income and related-product shocks:
| Elasticity Measure | Formula (Signed Value Matters!) | Sign / Range Classification | Economic & UPSC Exam Application |
|---|---|---|---|
| 1. Income Elasticity of Demand (Ey) | %Δ Quantity Demanded ÷ %Δ Consumer Income | • 0 < Ey < 1: Normal Necessity • Ey > 1: Normal Luxury / Superior • Ey < 0: Inferior Good |
Explains Engel’s Law: because food has 0 < Ey < 1, as household income rises, total food spending rises in rupees while the share of income spent on food falls! |
| 2. Cross-Price Elasticity of Demand (Exy) | %Δ Quantity Demanded of X ÷ %Δ Price of Y | • Exy > 0 (Positive): Substitutes • Exy < 0 (Negative): Complements • Exy = 0: Unrelated Goods |
A higher tea price raises coffee demand (Exy > 0); higher petrol prices reduce petrol-car demand (Exy < 0). Used by competition regulators to define market boundaries. |
| 3. Giffen vs Veblen Upward-Sloping Exceptions | Own-price response (ΔQ / ΔP > 0) via opposite mechanisms | • Giffen: Poverty-driven inferior staple • Veblen: Prestige-driven luxury good |
Giffen arises from crushing real-income loss on a poor household’s staple; Veblen arises from conspicuous status signalling where high price itself confers exclusivity. |
6. Prices Coordinate Choices — Yet Do Not Settle Every Social Question
Market prices perform three decentralised coordination roles simultaneously without any central agency knowing every citizen’s preferences or every firm’s cost sheet:
- Information / Signalling Function: Rising prices broadcast growing relative scarcity or stronger demand; falling prices broadcast abundance or slack demand.
- Incentive Function: Higher prices reward producers who expand output or innovate substitutes and encourage buyers to conserve; lower prices redirect resources elsewhere.
- Rationing Function: Allocates scarce existing units to buyers willing and able to pay at least the market price.
Crucially, rationing by ability to pay is not allocation by human urgency: a malnourished child’s family has far fewer rupee “votes” in a market than an affluent buyer purchasing luxury pet food. Moreover, unregulated prices omit external pollution damages, under-supply public goods, and distort outcomes under monopoly power or hidden quality defects — explaining why societies pair price coordination with social protection and regulation.
7. Price Controls Change How the Market Adjusts
When governments cap or prop up prices for social or sectoral goals, supply-and-demand logic predicts the exact pressures created whenever legal limits block market-clearing adjustment:
7.1 Price Ceiling: A Legal Maximum Price
A price ceiling prohibits legal sales above a stated cap. It is binding (effective) only when set below the market equilibrium price (a ceiling set above ₹40 has zero direct effect because the market already trades at ₹40). In our lunch-box market (P* = ₹40, Q* = 60), a binding ceiling at ₹30 raises quantity demanded to 80 while cutting quantity supplied to 40 — creating a persistent shortage of 40 boxes. Because legislation lowers the price tag without conjuring extra vegetables or cooks, scarce units end up rationed via queues, waiting time, ration cards, seller favouritism, quality dilution, or illegal black-market premiums unless backed by public supply expansion or transparent rationing. Notice the distributional split: buyers who actually secure the good at ₹30 gain affordability, while excluded buyers lose access altogether.
7.2 Price Floor: A Legal Minimum Price (vs Guaranteed Procurement)
A price floor prohibits legal sales below a stated minimum. It is binding only when set above the market equilibrium price. At a binding floor of ₹50 (> ₹40), sellers offer 80 boxes while private buyers purchase only 40 — creating an unsold surplus of 40 boxes. Keep two interventions strictly separate in UPSC exams: a legal price floor alone does not guarantee that sellers find buyers for all 80 units (actual private sales may shrink to 40, or distressed sellers may trade unofficially below the floor); absorbing the 40-unit surplus requires a separate public procurement commitment backed by budget outlays, storage warehouses, and distribution channels! Over longer horizons, as both demand and supply grow more elastic, the shortages from ceilings and surpluses from floors typically widen.
8. Taxes and Subsidies Separate the Buyer’s Price from the Seller’s Price
Introducing a per-unit indirect tax or per-unit subsidy drives a price wedge between what the buyer pays (Pb) and what the seller nets (Ps), revealing one of economics’ sharpest policy insights:
- Per-Unit Tax Wedge & Quantity Contraction: A tax per box pushes Pb up and pulls Ps down (Pb − Ps = Tax), normally reducing equilibrium traded quantity below the untaxed benchmark.
- Statutory Incidence ≠ Economic Incidence: Statutory incidence names who is legally required to write the tax cheque to the government; economic incidence measures whose real pocket bears the burden via higher buyer prices vs lower net seller receipts. In a competitive market, the economic split is identical regardless of which side legally remits the tax!
- The Golden Elasticity Rule & Exact Formula of Tax/Subsidy Incidence: The less elastic (less responsive) side of the market always bears the larger share of the tax burden — because it has fewer substitutes or exit options to escape the taxed trade! For a small per-unit tax $t$, the ratio of the buyer’s price rise ($\Delta P_b = P_b - P^*$) to the seller’s net price drop ($|\Delta P_s| = P^* - P_s$) equals the inverse ratio of their price elasticities: $$\frac{\text{Buyer Burden } (\Delta P_b)}{\text{Seller Burden } (|\Delta P_s|)} = \frac{E_s}{|E_d|} \implies \text{Buyer Share} = \frac{E_s}{|E_d| + E_s}, \quad \text{Seller Share} = \frac{|E_d|}{|E_d| + E_s}$$ If lunch buyers have almost no alternative ($|E_d|$ very low) while kitchens can easily switch to catering ($E_s$ high), buyers bear most of the tax via higher prices. Conversely, if office workers easily switch to home tiffins ($|E_d|$ high) while kitchens are locked into fixed leases and ovens ($E_s$ low), kitchens absorb most of the tax through lower net receipts. Because elasticities change between week one and year two, short-run incidence can differ sharply from long-run incidence.
- Per-Unit Subsidies Work in Reverse: A per-unit subsidy lowers Pb below Ps (Ps − Pb = Subsidy) and expands traded quantity, with the less elastic side capturing the larger price benefit of the public outlay.
8.1 Indian Policy Applications: MSP Procurement, Drug Price Ceilings, TOP Swings & Surplus
Connecting demand-supply wedges and controls to Indian policy arenas bridges Prelims concepts with GS Paper III answers:
- Minimum Support Price (MSP) as an Effective Floor Only Where Backed by Procurement: Announced MSP acts as an indicative floor; in paddy and wheat belts where FCI and State agencies execute open-ended procurement above market-clearing prices, excess supply accumulates as central-pool buffer stocks (carrying fiscal food-subsidy, storage, and crop-concentration trade-offs), whereas in crops/regions lacking procurement infrastructure, mandi prices often dip below MSP — illustrating our exact distinction between a stated floor and guaranteed purchase!
- Essential Drug & Medical-Device Price Ceilings (NPPA): Under the Drug Price Control Orders, the National Pharmaceutical Pricing Authority caps prices of scheduled essential medicines and coronary stents to protect patient affordability where demand is acutely price-inelastic — while requiring careful monitoring so overly compressed margins do not cause manufacturers to discontinue critical formulations.
- Perishable TOP (Tomato–Onion–Potato) Volatility & Buffer Intervention: Because short-run farm supply is biologically lagged and consumer demand is inelastic, weather shocks or lagged planting responses (cobweb cycles) trigger violent price spikes and gluts; India’s Price Stabilisation Fund and cold-chain investments raise effective supply elasticity by storing surpluses during harvest gluts and releasing stocks during lean-season spikes.
- Consumer Surplus, Producer Surplus & Deadweight Loss Intuition: Competitive equilibrium maximises the combined net gains of buyers paying less than their maximum willingness to pay (consumer surplus) and sellers receiving more than their minimum supply cost (producer surplus). Taxes or binding price controls shrink mutually beneficial trades (creating an efficiency deadweight loss), which policymakers weigh transparently against revenue, equity, environmental, or food-security objectives.
9. The Complete Market Story
Seen end to end, market price theory forms one disciplined reasoning chain: buyer willingness-and-ability schedules meet seller willingness-and-ability schedules → excess demand or excess supply generates price and non-price adjustment pressures → distinguishing own-price movements along curves from determinant shifts isolates true causes → elasticities quantify short-run and long-run responsiveness, total spending shifts, price-control gaps, and tax/subsidy incidence → and separating decentralised coordination from distributional fairness shows both why markets are indispensable and why public policy must complement them.
9.1 Concrete Worked Examples: Solving Linear Demand-Supply Equilibrium & Price Controls, Proving the Farmer’s Bumper-Harvest Paradox, and Computing Tax Incidence & Deadweight Loss
To apply demand-supply equations, elasticity formulas, price controls, and tax wedges with complete confidence in UPSC Prelims and GS Paper III Mains, work through these three step-by-step numerical examples:
Scenario: The daily office lunch-box market in Table 1 follows the linear equations: $$\text{Market Demand: } Q_d = 140 - 2P, \qquad \text{Market Supply: } Q_s = -20 + 2P$$ Verify the equilibrium, the effect of a ₹30 price ceiling, and the fiscal cost of a ₹50 price floor backed by public procurement:
- Unrestricted Market Equilibrium ($Q_d = Q_s$): $$140 - 2P^* = -20 + 2P^* \implies 160 = 4P^* \implies P^* = \mathbf{₹40}, \quad Q^* = 140 - 2(40) = \mathbf{60\text{ boxes}}$$
- Binding Price Ceiling at $P_c = ₹30$ ($< ₹40$): $$Q_d(30) = 140 - 2(30) = 80\text{ boxes}, \quad Q_s(30) = -20 + 2(30) = 40\text{ boxes}$$ Actual quantity traded drops to $\min(Q_d, Q_s) = \mathbf{40\text{ boxes}}$, creating a persistent shortage of $80 - 40 = 40\text{ boxes}$!
- Binding Price Floor at $P_f = ₹50$ ($> ₹40$): $$Q_d(50) = 140 - 2(50) = 40\text{ boxes}, \quad Q_s(50) = -20 + 2(50) = 80\text{ boxes}$$ Without procurement, private buyers purchase only $40\text{ boxes}$, leaving an unsold surplus of $80 - 40 = 40\text{ boxes}$. If a public procurement agency commits to buying the entire 40-box surplus at the ₹50 floor, it must spend $40 \times ₹50 = \mathbf{₹2,000\text{ per day}}$ in procurement outlays (plus storage and distribution costs).
Scenario: Following ideal monsoon rains, a region’s potato harvest expands from $Q_1 = 100\text{ lakh tonnes}$ to $Q_2 = 120\text{ lakh tonnes}$ ($+20\%$). Because consumer demand for staple potatoes is price-inelastic, the wholesale mandi price falls from $P_1 = ₹20/\text{kg}$ to $P_2 = ₹12/\text{kg}$ ($-40\%$). Compute the Arc Elasticity of Demand and the change in farmers’ Total Revenue ($TR = P \times Q$):
- Arc (Midpoint) Price Elasticity of Demand ($|E_d|$): $$\%\Delta Q = \frac{120 - 100}{(100 + 120)/2} = \frac{20}{110} = +18.18\%, \qquad \%\Delta P = \frac{12 - 20}{(20 + 12)/2} = \frac{-8}{16} = -50.0\%$$ $$\text{Arc } |E_d| = \frac{18.18\%}{50.0\%} = \mathbf{0.364 < 1\text{ (Strongly Price-Inelastic)}}$$
- Impact on Farmers’ Total Cash Revenue ($TR = P \times Q$):
- Normal Harvest Revenue ($TR_1$): $₹20 \times 100\text{ lakh tonnes} = \mathbf{₹2,000\text{ crore}}$
- Bumper Harvest Revenue ($TR_2$): $₹12 \times 120\text{ lakh tonnes} = \mathbf{₹1,440\text{ crore}}$
Scenario: Around an initial equilibrium of $P^* = ₹40$ and $Q^* = 60\text{ units}$, consumer demand has price elasticity $|E_d| = 0.4$ (inelastic) while producer supply has price elasticity $E_s = 0.6$ (more elastic). The government imposes a ₹10 per-unit excise tax, reducing equilibrium traded quantity to $Q_t = 54\text{ units}$. Find the buyer’s price, seller’s net price, tax revenue, and deadweight loss:
- Buyer vs. Seller Share of the ₹10 Tax Wedge: $$\text{Buyer Share} = \frac{E_s}{|E_d| + E_s} = \frac{0.6}{0.4 + 0.6} = \mathbf{60\%} \implies \Delta P_b = +₹6 \quad (P_b = ₹40 + ₹6 = \mathbf{₹46})$$ $$\text{Seller Share} = \frac{|E_d|}{|E_d| + E_s} = \frac{0.4}{0.4 + 0.6} = \mathbf{40\%} \implies \Delta P_s = -₹4 \quad (P_s = ₹40 - ₹4 = \mathbf{₹36})$$ Notice that $P_b - P_s = ₹46 - ₹36 = ₹10\text{ tax}$, and the less elastic side (buyers, $|E_d|=0.4 < E_s=0.6$) bears $60\%$ of the burden regardless of whether the statute collects the tax from buyers or sellers!
- Government Tax Revenue & Efficiency Deadweight Loss (DWL): $$\text{Tax Revenue} = \text{Tax} \times Q_t = ₹10 \times 54 = \mathbf{₹540}$$ $$\text{Deadweight Loss (Harberger Triangle)} = \frac{1}{2} \times \text{Tax} \times (Q^* - Q_t) = \frac{1}{2} \times ₹10 \times (60 - 54) = \mathbf{₹30}$$
UPSC CSE Prelims Previous Year Questions (PYQ Anchors)
Q1. Other things remaining unchanged, market demand for a good might increase if:
1. price of its substitute increases
2. price of its complement increases
3. the good is an inferior good and income of the consumers increases
4. its price falls
Which of the above statements are correct?
(a) 1 and 4 only (b) 2, 3 and 4 (c) 1, 3 and 4 (d) 1, 2 and 3
View Official Answer & Explanation
Correct Answer: (a) 1 and 4 only
Explanation: Statement 1 is correct (a higher price of a substitute shifts demand for the good rightward). Statement 2 is incorrect (a costlier complement reduces demand). Statement 3 is incorrect (when consumer income rises, demand for an inferior good falls as consumers shift to better alternatives). Statement 4 increases quantity purchased along the market demand schedule, giving (a) 1 and 4 only per UPSC’s official key.
Q2. Which of the following statements accurately describes the relationship between Inferior Goods and Giffen Goods?
(a) Every inferior good is necessarily a Giffen good, exhibiting an upward-sloping demand curve.
(b) Every Giffen good must be an inferior good whose negative income effect is strong enough to outweigh its substitution effect, whereas most inferior goods still obey the downward-sloping Law of Demand.
(c) Giffen goods are luxury status symbols bought by high-income consumers.
(d) Neither inferior goods nor Giffen goods respond to changes in real purchasing power.
View Official Answer & Explanation
Correct Answer: (b)
Explanation: Most inferior goods still have a downward-sloping own-price demand curve because the substitution effect dominates. Only in the rare case where a poor household spends so large a budget share on an inferior staple that the negative income effect overwhelms the substitution effect does a good become a Giffen good (whereas luxury status-symbol demand is the distinct Veblen effect).
Q3. Suppose the government imposes a new per-unit excise duty on a commodity whose consumer demand is highly price-inelastic while producer supply is relatively price-elastic. Even if the tax statute requires manufacturers to remit the full duty to the treasury:
(a) Manufacturers will bear virtually the entire economic burden through lower profits.
(b) Consumers will bear the larger share of the economic burden through a higher retail price.
(c) Equilibrium traded quantity will expand sharply.
(d) Statutory incidence always equals 100% of economic incidence.
View Official Answer & Explanation
Correct Answer: (b)
Explanation: Economic tax incidence depends on relative elasticities, not on who legally remits the cheque: because consumers are much less price-responsive than producers here (|Ed| < Es), the bulk of the tax is passed forward into a higher buyer price.
Q4. Consider a competitive market whose unrestricted equilibrium price is ₹40 per kg:
1. A legal price ceiling fixed at ₹50 per kg is binding and creates an immediate market shortage.
2. A legal price floor fixed at ₹50 per kg is binding and creates excess supply (surplus) unless absorbed by separate public procurement.
Which of the statements given above is/are correct?
(a) 1 only (b) 2 only (c) Both 1 and 2 (d) Neither 1 nor 2
View Official Answer & Explanation
Correct Answer: (b) 2 only
Explanation: Statement 1 is false because a maximum price cap (ceiling) at ₹50 lies above the ₹40 equilibrium and is therefore non-binding (ceilings bind only below equilibrium). Statement 2 is correct: a minimum price floor at ₹50 lies above ₹40, inducing excess supply unless matched by separate procurement.
Quick Revision Takeaways for Prelims & Mains
- Movement Along vs Shift: Own-price change → movement along curve (change in quantity demanded/supplied). Non-price determinant change → shift of the entire curve.
- Shortage ≠ Scarcity: Scarcity is universal; a shortage (Qd > Qs) occurs specifically when price sits below market-clearing equilibrium.
- Simultaneous Shifts: Both D ↑ & S ↑ ⇒ Q* definitely rises, P* indeterminate; D ↑ & S ↓ ⇒ P* definitely rises, Q* indeterminate.
- Elasticity & Total Revenue: Unit-free (%ΔQ ÷ %ΔP) ≠ slope! When own price rises ceteris paribus, Total Spending (P × Q) rises if demand is inelastic (<1) and falls if demand is elastic (>1).
- Ceilings, Floors & Tax Incidence: Ceilings bind below P* (shortage); Floors bind above P* (surplus; legal floor ≠ guaranteed purchase!). The less elastic side always bears more of a tax burden and captures more of a subsidy’s price benefit.
Prelims Practice MCQs (8 Market & Price-Theory Questions)
MCQ 1. Which of the following events causes a movement along the existing market demand curve for tea rather than a shift of the tea demand curve?
(a) A sharp rise in the retail price of coffee (a close substitute)
(b) An increase in household disposable incomes across cities
(c) A harvest-led fall in the retail price of tea itself, with incomes and coffee prices unchanged
(d) A viral medical advisory warning people against caffeine
Show Answer
Answer: (c) — A supply-driven change in tea’s own price moves buyers along their unchanged tea demand curve; (a), (b), and (d) shift the entire demand curve.
MCQ 2. Suppose a metro rail authority raises peak-hour ticket fares by 10% and observes that peak-hour ridership falls by only 3% while total daily fare revenue increases. Over this range, peak-hour metro demand is:
(a) Price elastic (|Ed| = 3.33)
(b) Price inelastic (|Ed| = 0.30)
(c) Perfectly elastic
(d) Unit elastic (|Ed| = 1.0)
Show Answer
Answer: (b) — |Ed| = 3% ÷ 10% = 0.30 (< 1, inelastic), which directly explains why total fare revenue rose when price increased.
MCQ 3. During the festival season, consumer demand for sweets shifts rightward at the exact same time that a bumper sugar and milk harvest shifts sweet supply rightward. Without knowing the exact magnitudes of the two shifts, what can be concluded with certainty?
(a) Equilibrium price will definitely rise, while equilibrium quantity may rise or fall.
(b) Equilibrium quantity traded will definitely rise, while equilibrium price may rise, fall, or stay unchanged.
(c) Both equilibrium price and equilibrium quantity will definitely fall.
(d) Neither price nor quantity can change.
Show Answer
Answer: (b) — Both rightward shifts push quantity upward, while Demand ↑ pushes price up and Supply ↑ pulls price down, making net price movement dependent on relative shift sizes.
MCQ 4. Why does a linear downward-sloping demand curve NOT have constant price elasticity along its entire length?
(a) Because its slope changes at every point.
(b) Because elasticity is the ratio of percentage changes ((ΔQ/Q) ÷ (ΔP/P)): even when ΔQ/ΔP is constant, high P and tiny Q near the top make percentage Q changes huge (elastic), whereas low P and large Q near the bottom make percentage Q changes small (inelastic).
(c) Because the Law of Demand fails on straight lines.
(d) Because units of currency alter elasticity.
Show Answer
Answer: (b) — Constant slope (ΔP/ΔQ) combined with changing base ratio (P/Q) causes elasticity to vary continuously along a straight demand line.
MCQ 5. If farmers expect onion prices to be substantially higher two months from now and possess dry storage structures, what happens in today’s spot onion market (holding current consumer preferences unchanged)?
(a) Today’s supply curve shifts leftward as farmers withhold stock for future sale, putting upward pressure on today’s spot price.
(b) Today’s supply curve shifts rightward, crashing today’s spot price.
(c) Farmers move downward along an unchanged supply curve.
(d) Onion becomes a public good.
Show Answer
Answer: (a) — Higher expected future prices raise the opportunity cost of selling storable output today, shifting current market supply leftward.
MCQ 6. Which of the following best explains why shortages caused by a binding rent/price ceiling often grow more severe over five years than in the first month?
(a) Both demand and supply typically become less elastic over longer periods.
(b) Over several years, supply becomes much more elastic (landlords halt maintenance, convert buildings, or build fewer new rental units) and buyers adjust habits, widening the gap between quantity demanded and quantity supplied.
(c) Ceilings automatically turn non-binding over time.
(d) Inflation never changes real prices.
Show Answer
Answer: (b) — Short-run housing supply is nearly fixed, keeping the month-one gap small; long-run supply adjustment widens the shortage substantially.
MCQ 7. A government introduces a ₹20 per unit subsidy paid to solar-lantern buyers, in a market where village household demand is highly price-elastic while local assembly capacity is tightly bottlenecked (inelastic supply) in the short run. Who captures the larger share of the immediate price benefit?
(a) Buyers capture 100% via a ₹20 drop in net price.
(b) Sellers (the less elastic side in the short run) capture the larger share as market prices bid up against tight capacity, until capacity expands in the long run.
(c) Neither buyers nor sellers receive any benefit.
(d) Traded quantity falls.
Show Answer
Answer: (b) — Just as the less elastic side bears more of a tax, the less elastic side captures more of a subsidy’s price shift — underscoring why demand subsidies work best when paired with supply-side capacity expansion!
MCQ 8. Which statement accurately distinguishes market coordination from social optimality?
(a) Market-clearing equilibrium guarantees zero hunger and zero pollution.
(b) Market equilibrium reconciles the plans of buyers backed by purchasing power and sellers covering private costs, yet can coexist with unmet basic needs of poor households, unpriced pollution externalities, or concentrated market power.
(c) Market prices carry zero information about scarcity.
(d) Administered price controls never create trade-offs.
Show Answer
Answer: (b) — Equilibrium proves plan compatibility under existing income distribution and private costs, not ethical perfection or absence of externalities.
GS Paper III Mains Practice Questions
Mains Q1 (GS Paper III — 15 Marks, 250 Words): Using the microeconomic tools of price elasticity, supply lags, and price floors/ceilings, analyse why perishable agricultural commodities in India experience sharp seasonal price swings and evaluate why isolated retail price caps often struggle without cold-chain and supply-side reforms.
Structuring Blueprint:
- Introduction: Highlight how staple/perishable farm markets combine inelastic short-run consumer demand with weather-sensitive, biologically lagged supply.
- Elasticity & Volatility Mechanism: Show why even a modest harvest shock or transport disruption causes steep price spikes (or post-harvest gluts crash farm-gate prices, reducing farmers’ total revenue because demand is inelastic!).
- Limits of Standalone Price Controls: Explain how binding retail price ceilings/export bans compress farmer incentives without creating missing cold stores, while legal floors without procurement/diversification create localised surpluses in select crops.
- Conclusion: Recommend raising supply elasticity via cold chains, processing, e-NAM/FPO aggregation, predictable trade rules, and targeted consumer protection for vulnerable households.
Mains Q2 (GS Paper III — 10 Marks, 150 Words): Distinguish between statutory tax incidence and economic tax incidence. How does understanding demand and supply elasticities help policymakers design indirect tax and subsidy reforms?
Structuring Blueprint:
- Introduction: Contrast statutory remittance duty with post-adjustment economic burden across buyers and sellers.
- Role of Relative Elasticities: Explain why taxing price-inelastic necessities burdens low-income consumers heavily while generating steady revenue, whereas taxing elastic luxury/polluting items induces stronger behavioural shifts; show symmetrically why consumer subsidies require elastic supply capacity lest subsidies merely bid up producer prices.
- Conclusion: Tie elasticity-aware design to equitable GST rate structure and green fiscal incentives.
Frequently Asked Questions (FAQs)
Q1. Does “inferior good” mean a low-quality, adulterated, or defective product?
No. In economics, “inferior” is purely an income-response classification: a good whose demand falls when a consumer’s real income rises because the consumer shifts toward preferred alternatives (for instance, shifting from crowded non-AC bus travel to metro or cab travel as income grows).
Q2. Why can a bumper harvest sometimes leave farmers with lower total cash revenue than a normal harvest?
Because household demand for staple foodgrains and vegetables is typically price-inelastic (|Ed| < 1): when a bumper harvest shifts supply sharply rightward, the percentage drop in farm-gate market price can exceed the percentage rise in quantity sold, causing total market revenue (P × Q) to fall unless storage, food processing, export outlets, or price-support procurement absorb the extra output.
Q3. Is announcing a legal minimum price the same thing as buying every unit producers offer?
No. A legal price floor forbids transactions below the stated price, which creates excess supply if set above market equilibrium; absorbing that surplus requires a separate fiscal and logistical public-procurement operation.
10. Primary Policy Reports, Statutory Orders & Official Sources
- Microeconomic Foundations: NCERT, Introductory Microeconomics (Class XII: Theory of Consumer Behaviour, Production and Costs, and Market Equilibrium).
- Agricultural Price Policy & Buffer Operations: Commission for Agricultural Costs and Prices (CACP), Ministry of Agriculture and Farmers Welfare, Price Policy Reports for Kharif and Rabi Crops; and Department of Consumer Affairs, Price Stabilisation Fund (PSF) Operational Guidelines.
- Statutory Price Controls & Competition Law: National Pharmaceutical Pricing Authority (NPPA), Drugs (Prices Control) Order (DPCO) under the Essential Commodities Act, 1955; and Competition Commission of India (CCI), Competition Act, 2002 (Relevant Market & Cross-Elasticity Assessment).